Treasuries Led September’s Sell Off. EM Debt Held Its Ground
08 October 2026
Read Time 8 MIN
Key Takeaways
- EM bonds outperformed again as the “risk-free” asset led the selloff. EMBX is up 1.41% YTD versus -5.15% for US 10Y Treasuries, a 656 bp gap that widened from 572 bp last month.
- EMs generally have lower debt, higher real rates, and independent central banks focused on inflation. DMs have the opposite.
- September’s repricing happened one CDS at a time. Oracle and France CDS were sparks in re-evaluating the US AI trade and Eurozone sovereigns. Once spreads widen, funding costs rise for the borrowers least able to absorb them, and the initial conditions reinforce themselves.
- EMBX’s yield to worst is 7.55%.
September Performance
The VanEck Emerging Markets Bond ETF (EMBX) returned -2.65% in September, compared to -2.86% for its benchmark, the 50% J.P. Morgan Government Bond Index - Emerging Markets Global Diversified (GBI-EM) and 50% J.P. Morgan Emerging Markets Bond Index (EMBI), and -2.72% for the Global Agg and -3.65% for US 10Y Treasuries. Year to date, EMBX is up 1.41%, compared to -0.04% for its benchmark, -3.66% for the Global Agg and -5.15% for US 10Y Treasuries. Mexico local (underweight), Czechia local, and Saudi Arabia hard (underweight) contributed most to outperformance in September, while Senegal hard detracted the most. Local currency exposure is currently 42.25%, carry is 6.64%, yield to worst is 7.55%, and duration decreased to 4.57 years.
| Month End As of 09/30/2026 | 1 MO | 3 MO | YTD | 1 YR | 3 YR | 5 YR | 10 YR | LIFE 07/09/12 |
| EMBX (NAV) | -2.65 | -2.12 | 1.41 | 4.61 | 10.51 | 4.68 | 4.84 | 3.48 |
| EMBX (Market Price) | -2.86 | -2.29 | 1.24 | 4.31 | 10.40 | 4.62 | 4.81 | 3.46 |
| 50% GBI-EM/50% EMBI | -2.73 | -2.41 | -0.03 | 3.28 | 8.97 | 2.29 | 2.66 | 2.54 |
*Returns less than one year are not annualized.
EMBX Gross Expense Ratio - 0.76%
30 Day SEC Yield: 5.99% as of October 5, 2026
View the EMBX Prospectus here.
The performance data quoted represents past performance. Past performance is not a guarantee of future results. Investment return and principal value of an investment will fluctuate so that an investor's shares, when redeemed, may be worth more or less than their original cost. Performance may be lower or higher than performance data quoted. Please call 800.826.2333 or visit vaneck.com for performance current to the most recent month ended.
Prior to 10/06/2025, the Fund operated as the VanEck Emerging Markets Bond mutual fund; performance shown before that date is that fund's NAV performance (Class I, unadjusted for today's ETF expenses).
DM bonds, US Treasuries in particular, drove September’s global rates sell off.
EMBX fell 2.65%, a full point less than Treasuries and in line with the Global Agg, despite EM’s higher volatility. That outperformance in vol-adjusted terms has been the pattern for a couple of decades already (see our many white papers on this topic). Last month we told you the ugly ducklings were quacking louder. In September the farm’s favorite bird stumbled again. Treasuries are now down 5.15% year to date. EMBX is up 1.41%, and Chinese onshore bonds are up 6.37% in dollar terms, having gained again in September while Treasuries sold off. That’s 656 basis points between EMBX and Treasuries, wider than the 572 we flagged last month, and over 1,100 between Chinese bonds and Treasuries. The sign is still on the wrong side for the asset that is supposed to be the anchor of the system. Notice what happened in a month when the “risk-free” asset led the sell off: the asset meant to absorb risk exported it, and the asset meant to carry risk held up. The chart below barely earns its place; at this stage the story tells itself.
Exhibit 1 – Low/Stable Inflation in EM Means Declining Local Borrowing Costs
GBI-EM/5Y UST Yield Differential vs Trend and Volatility Bands (bps)


10y UST Yield with Volatility Bands (%)

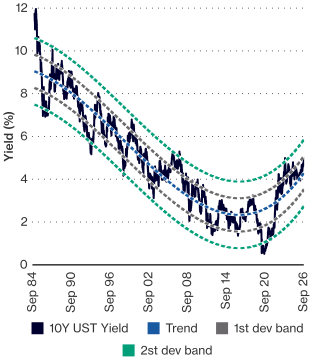
Source: VanEck Research; Bloomberg LP. Data as of September 2026. Past performance is not indicative of future results. Index performance is not illustrative of fund performance. It is not possible to invest directly in an index.
Why Do DM Bonds Keep Losing?
Initial conditions for the DM are the opposite of those in many EMs. DM debt levels are high, real rates are too low, structure (e.g., the Eurozone) is weak, and the politics are degenerating. EMs generally have low debt, high real rates, unlevered and less complex structures, and politics that don’t entertain using central banks to achieve outcomes other than low inflation. None of this is news; it is an initial condition, and much flows from (and is reflected in) it. This month’s portfolio changes, detailed below, read like a catalogue of the EM side of that ledger. Malaysia hiked pre-emptively. Colombia’s central bank chose to frontload tightening while the new cabinet signals fiscal adjustment. Hungary plans a lower inflation target. Indonesia promised fiscal consolidation in 2027. That is EM policymakers using their tools for the job they were given. Compare the DM, where central banks end up enabling a fiscal authority and lean on the income-inequality-magnifying “portfolio balance channel” (i.e., ginning up markets). Is it new news that this ends badly? Thank goodness for currency markets.
The outcomes make this point, and reinforce the problems. Oracle’s credit default swap (CDS) was a spark in the re-evaluation of the US “AI trade.” France CDS was a spark in the re-evaluation of the Eurozone sovereigns. September showed how the farm finds out: one credit default swap at a time. Neither the leverage behind the AI build-out nor France’s debt and the Eurozone’s structural weakness was news. What changed was that the market started pricing them. Once it does, wider spreads raise funding costs for exactly the borrowers least able to afford them, and the initial conditions start reinforcing themselves.
Exhibit 2 – CGBs Rallying During Major Risk Event, Treasuries Not
USTs vs CGBs in 2026 YTD (total return, %)
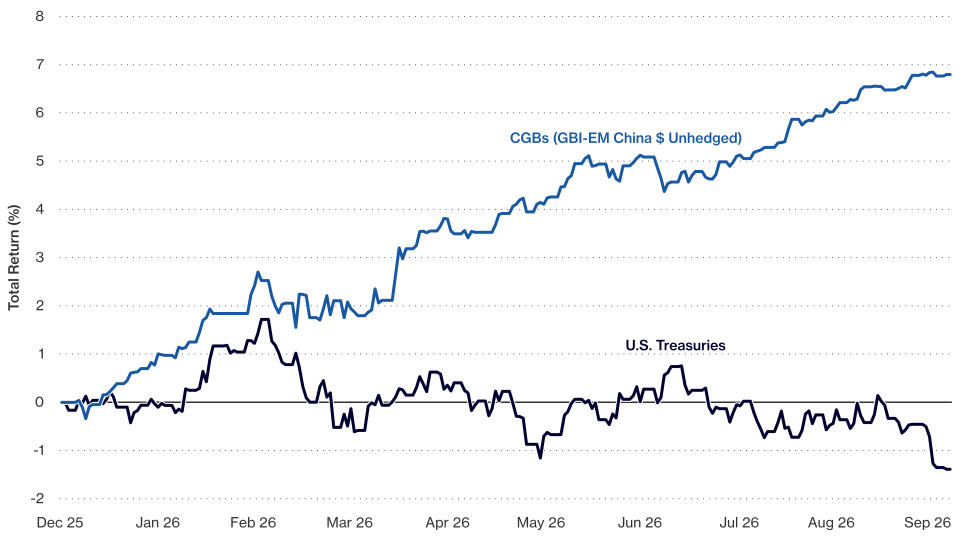
Source: VanEck Research; Bloomberg LP. Data as of September 2026. Not intended as a prediction of future results. For illustrative purposes only. Past performance is no guarantee of future results.
It’s normal for it to unfold this way. How many G-10 sell-side economists (your author is a “recovered” one) talked about loss of USD reserve status, or gold, before the past year or so, when global central bank action forced it on them? Your author spent many wonderful (seriously) hours debating his G-10 economist colleagues. My argument was that all of their charts were wrong, because they assume or imply that FX=1. Think about it: every chart you were taught with assumes an FX whose value is 1. Drop that assumption and you are in our more complicated world, a world in which “fiscal dominance” is not a fringe scenario but the inevitable corner solution. In all those hours, the only counter I ever received was that this is unlikely, or distant. Still think so?
Exposure Types and Significant Changes
The changes to our top positions are summarized below. Our largest positions in September were Brazil, Malaysia, China, Indonesia, and Poland:
- We increased our local currency exposure in Brazil and Colombia. Brazil’s presidential race turned more competitive than earlier polls suggested. The improving odds of the opposition candidate improve the chances of an orthodox post-election policy adjustment, especially on the fiscal side. Colombia’s new cabinet is sending strong fiscal adjustment signals, while the central bank chose to frontload more policy tightening. In terms of our investment process, this improved the policy test scores in both countries.
- We also increased our local currency exposure in Malaysia, Indonesia, and Taiwan. Malaysia’s pre-emptive rate hike strengthened support for the currency and duration, while the country is finally jumping on the AI/datacenter bandwagon, which should support external surpluses for years to come. These developments strengthened the economic and policy test scores for the country. Indonesia’s authorities sent several orthodox policy signals, including [the confirmation of the central bank governor], the new market-friendly minister of finance, and a promise of fiscal consolidation in 2027, improving the policy test score for the country. Taiwan’s AI narrative remains intact, while the currency can benefit from its high correlation with the Chinese renminbi. These factors improved the economic and technical test scores for the country.
- Finally, we increased our local currency exposure in Hungary and hard currency sovereign exposure in Suriname. The Hungarian authorities now plan to adopt a lower inflation target. That supports the currency by limiting room for rate cuts in the near term, and supports longer-dated rates through added credibility. In terms of our investment process, this improved the policy test score for the country. Suriname can benefit from both higher oil and gold prices, and the improving macroeconomic backdrop can pave the way for a rating upgrade. In the meantime, these developments lifted the economic test score for the country.
- We reduced our local currency exposure in South Africa, where we see no obvious positive catalysts, while high oil prices are a challenge for disinflation, which might require additional policy tightening. Domestic politics can also become noisier going into the next election cycle. These developments worsened the technical and policy test scores for the country.
- We also reduced our local currency exposure in Mexico and Thailand. Mexico’s lack of new catalysts is a drawback, especially with other, brighter stories in the region, while the targeted 2027 fiscal consolidation is very small. These factors worsened the policy and technical test scores for Mexico. Thailand is a regional low yielder that is also losing out to cheaper manufacturing exports from China. The country is not participating in the AI boom, while the central bank’s space to tighten is limited by slowing growth, just as fiscal space is getting stretched. These developments worsened the economic and policy test scores for the country.
- Finally, we reduced our hard currency sovereign exposure in Senegal and Paraguay. Paraguay’s main problem is less attractive valuations, whereas Senegal is now dealing with a noisy and very complicated debt restructuring, which significantly worsened its policy test score.
Important Disclosures
There is no guarantee that these conditions will persist or that the fund will achieve similar results in the future.
This is not an offer to buy or sell, or a recommendation to buy or sell any of the securities, financial instruments or digital assets mentioned herein. The information presented does not involve the rendering of personalized investment, financial, legal, tax advice, or any call to action. Certain statements contained herein may constitute projections, forecasts and other forward-looking statements, which do not reflect actual results, are for illustrative purposes only, are valid as of the date of this communication, and are subject to change without notice. Actual future performance of any assets or industries mentioned are unknown. Information provided by third party sources are believed to be reliable and have not been independently verified for accuracy or completeness and cannot be guaranteed. VanEck does not guarantee the accuracy of third party data. The information herein represents the opinion of the author(s), but not necessarily those of VanEck or its other employees.
Duration measures a bond’s sensitivity to interest rate changes that reflects the change in a bond’s price given a change in yield. This duration measure is appropriate for bonds with embedded options. Carry is the benefit or cost for owning an asset. Yield to worst is a measure of the lowest possible yield that can be received on a bond with an early retirement provision. Averages are market weighted. The yields presented do not represent the performance of the Fund. These statistics do not take into account fees and expenses associated with investments of the Fund.
30-Day SEC Yield is a standard yield calculation developed by the Securities and Exchange Commission that allows for fairer comparisons among funds. It is based on the most recent 30-day period. This yield figure reflects the interest earned during the period after deducting the Fund’s expenses for the period. It does not reflect the yield an investor would have received if they had held the Fund over the last twelve months assuming the most recent NAV.
All indices are unmanaged and include the reinvestment of all dividends, but do not reflect the payment of transaction costs, advisory fees or expenses that are associated with an investment in the Fund. Certain indices may take into account withholding taxes. An index’s performance is not illustrative of the Fund’s performance. Indices are not securities in which investments can be made.
The Fund’s benchmark index (50% GBI-EM/50% EMBI) is a blended index consisting of 50% J.P. Morgan Government Bond Index-Emerging Markets (GBI-EM) Global Diversified and 50% J.P. Morgan Emerging Markets Bond Index (EMBI). The J.P. Morgan GBI-EM Global Diversified tracks local currency bonds issued by Emerging Markets governments. The J.P. Morgan EMBI Global Diversified tracks returns for actively traded external debt instruments in emerging markets, and is also J.P. Morgan’s most liquid U.S. dollar emerging markets debt benchmark.
The Bloomberg Global Aggregate Index measures the performance of global investment grade fixed income securities.
The FTSE 10-Year US Treasuries Index measures the return of the 10-year U.S. Treasury.
An investment in the VanEck Emerging Markets Bond ETF may be subject to risks which include, among others, risks related to active management, credit, credit-linked notes, currency management strategies, derivatives, emerging market issuers, ESG investing, foreign currency, foreign securities, hedging, high portfolio turnover, high yield securities, interest rate, market, non-diversified, operational, restricted securities, investing in other funds, sovereign bond, special risk considerations of investing in African, Asian, and Latin American issuers, authorized participant concentration, no guarantee of active trading market, trading issues, fund shares trading, premium/discount and liquidity of fund shares, and cash transactions risks, all of which may adversely affect the Fund. Emerging market issuers and foreign securities may be subject to securities markets, political and economic, investment and repatriation restrictions, different rules and regulations, less publicly available financial information, foreign currency and exchange rates, operational and settlement, and corporate and securities laws risks.
Investing involves substantial risk and high volatility, including possible loss of principal. An investor should consider the investment objective, risks, charges and expenses of a Fund carefully before investing. To obtain a prospectus and summary prospectus, which contain this and other information, call 800.826.2333 or visit vaneck.com. Please read the prospectus and summary prospectus carefully before investing.
© Van Eck Securities Corporation, Distributor, a wholly-owned subsidiary of Van Eck Associates Corporation.
Related Insights

Related Insights
11 September 2026
11 September 2026
EM bonds, gold, and Chinese government bonds are rising while the assets built to absorb risk are falling. The market is rethinking what counts as safe.
28 August 2026
A debt sustainability framework for a Venezuelan bond restructuring, and what it implies for recovery values.
10 August 2026
Fiscal dominance, sanctions, and war footings are combining to make DM risks clearer to markets, with Japan and Europe as the key focal points.
16 July 2026
When global risk fades, EM fundamentals take center stage; and right now, inflation discipline, high real rates, and Chinese bond resilience make a compelling case for the asset class.
09 June 2026
EM bonds keep winning: low debt, commodity exports, and political tailwinds favor EM over stagflation-plagued DM - but active positioning matters, as not all EMs are created equal.