Where to Find Value in High Yield Bonds
29 January 2020
Read Time 5 MIN
High yield bond spreads and yields have steadily declined since their most recent peak in early 2016, notwithstanding a small but meaningful widening in 2018. This reflects slow but generally steady economic growth globally, and a continued search for yield. Although yields are tight by historical standards, comparisons between different segments of the global high yield market reveal potential opportunities. For example, although absolute yields of emerging markets high yield corporate bonds have tightened in recent years, we believe the yield pickup over U.S. high yield compares favorably from an historical perspective. The excess yield of emerging markets over U.S. high yield corporate bonds currently exceeds the levels of 2016, when credit spreads overall peaked, as well as the average level since then.
Attractive Yield Pickup for Emerging Markets High Yield Over U.S. High Yield
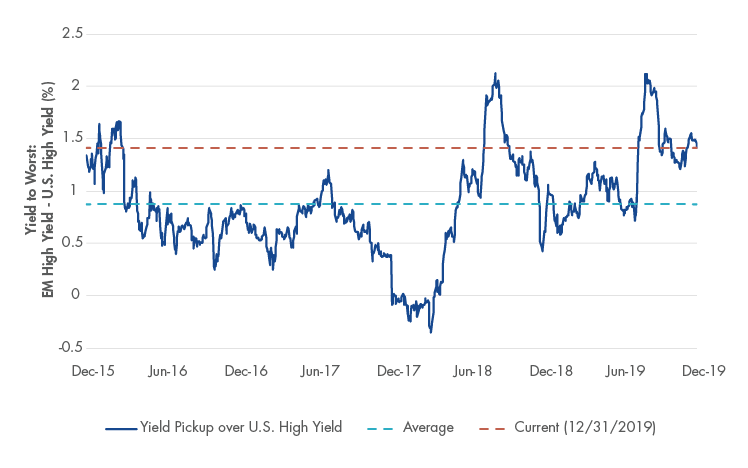
Source: ICE Data Indices. Data as of 12/31/2019
We believe this relative value opportunity is perhaps even more attractive in light of the robust credit fundamentals the asset class exhibits, which compare favorably to U.S. high yield corporates – from both a static and directional point of view. For example, interest coverage ratios among emerging markets high yield issuers were nearly 20% higher than U.S. counterparts, while net leverage was 20% lower, and the 2019 default rate among emerging markets high yield issuers was lower than the U.S. high yield default rate. Further, the asset class has a higher tilt towards higher rated high yield bonds. Continued dovish central bank policy, thawing U.S./China trade tensions and an uptick in global growth may help to offset macro uncertainty, while larger strategic allocations from global investors and favorable net issuance supply trends may also provide support.
For more on emerging markets bonds exposure in the current environment, watch this video with Fran Rodilosso, Emerging Markets Debt: Yield and Diversification.
Related Insights

Related Insights
11 September 2026
11 September 2026
EM bonds, gold, and Chinese government bonds are rising while the assets built to absorb risk are falling. The market is rethinking what counts as safe.
28 August 2026
A debt sustainability framework for a Venezuelan bond restructuring, and what it implies for recovery values.
10 August 2026
Fiscal dominance, sanctions, and war footings are combining to make DM risks clearer to markets, with Japan and Europe as the key focal points.
16 July 2026
When global risk fades, EM fundamentals take center stage; and right now, inflation discipline, high real rates, and Chinese bond resilience make a compelling case for the asset class.
09 June 2026
EM bonds keep winning: low debt, commodity exports, and political tailwinds favor EM over stagflation-plagued DM - but active positioning matters, as not all EMs are created equal.