Disinflation, Pivots – Easy Does It?
12 December 2022
Read Time 2 MIN
FED Pivot Prospects
This week, all eyes are on the U.S. inflation print and the Federal Reserve’s (Fed) rate-setting meeting. The consensus view is that further disinflation will allow the Fed to slow the pace of rate hikes to 50bps, with this cycle’s terminal rate peaking at 5%. Fed Funds Futures continue to price in 40-50bps of rate cuts in the second half of 2023, which many consider a stretch, given that U.S. inflation might still be above 3% by the end of the next year (if the current consensus forecast were to materialize).
EM Disinflation, Rates
Meanwhile, emerging markets (EM) inflation releases continue to send dovish signals, starting with a sizable downside surprise in India, where headline inflation actually moved back to the target range in November (5.88% year-on-year). The Indian central bank had just delivered a 35bps rate hike, and today’s print raises a possibility of a pause at the next meeting in February. Headline inflation in the Czech Republic exceeded expectations, accelerating to 16.2% year-on-year, but it was well below the peak, and core price pressures are moderating. Against this backdrop, there is no reason for the central bank to get alarmed. The market expectations that the policy pause will be extended into Q1-2023 look reasonable, albeit the pace of subsequent easing will depend on the growth trajectory and the disinflation progress.
China Stimulus
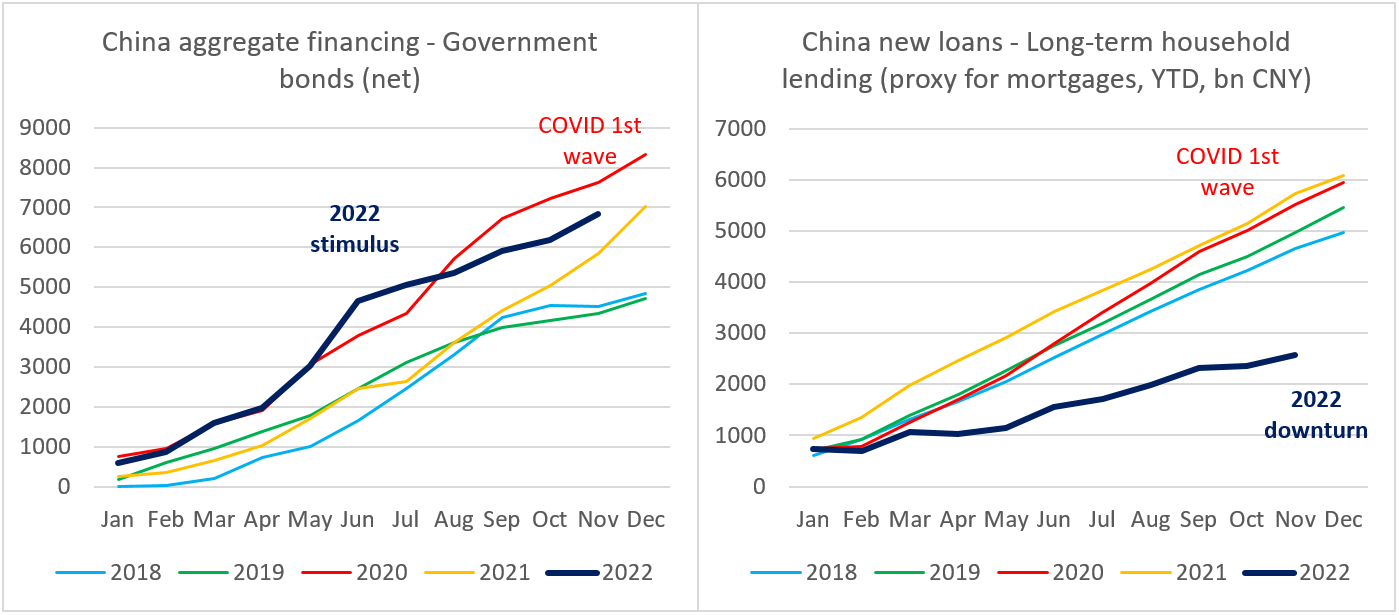
China’s inflation continued to moderate in November, but this should be expected to change if reopening gains pace. November’s credit aggregates also showed that the latest policy shift gave a small sequential boost to corporate and household lending (including mortgages). However, the improvement is very gradual – both new loans and aggregate financing surprised to the downside – and it remains to be seen whether (or when) authorities can stop relying on government bond issuance to prop up growth (see chart below), raising a bunch of concerns about leverage (again). Stay tuned!
Chart at a Glance: China Credit Growth – Different Dynamics
Source: Bloomberg LP
Related Insights

Related Insights
20 October 2026
17 September 2026
20 October 2026
Rising yields and oil prices pressured equities as the Fed raised rates 25 bps, while Moderna led BUZZ Index gains on oncology optimism and IREN weighed on returns.
17 September 2026
Rising oil prices and climbing Treasury yields pressured equities as the Fed left further tightening on the table, while Strategy led BUZZ Index gains on a bitcoin rally and commercial space names weighed on returns.
13 August 2026
See how Jan van Eck's Q3 outlook can be translated into actionable ETF ideas across semiconductors, private credit, gold and bitcoin.
17 July 2026
U.S. equities advanced despite geopolitical volatility and shifting rate expectations, but high-sentiment names lagged as investors grew more selective across AI infrastructure and growth stocks.
10 February 2026
Debasement is back in focus. Here’s what’s driving it, what could reverse it and how we’re positioning portfolios for both scenarios.