Higher for Longer - Market Not So Sure
15 December 2022
Read Time 2 MIN
Slower Rate Hikes in DM
The pace of tightening is slower (+50bps is the rate hike “du jour”), and the central banks’ message is hawkish, but the market does not seem to be fully convinced about the “higher for longer” narrative – at least in developed markets (DM). The reaction of U.S. Treasury yields during the U.S. Federal Reserve (Fed) Chairman’s press conference was quite telling (down). As of this morning, Fed Funds Futures continued to price the peak rate of less than 5% and about 50bps of rate cuts in H2-2023 (fully offsetting expected H1-2023 rate hikes). One reason is that even though inflation is well above the respective targets, the risk of recession in DM is quite high. The probability of recession in the U.S. 12 months from now, calculated by the New York Federal Reserve, rose to 38% (see chart below). The Bloomberg consensus forecast sees negative 2023 real GDP growth in the Eurozone and the U.K. The next batch of domestic activity gauges in DM – out tomorrow – will be closely watched, for sure.
EM Disinflation
The pace of hikes in emerging markets (EM) is also slowing – the Philippines opted for “fashionable” 50bps this morning, and the central bank of Mexico is expected to follow suit in the afternoon. Mexico finally started to show signs of disinflation – the latest set of bi-weekly numbers was particularly encouraging because it showed moderation both in headline and core price pressures. The slower pace of hikes in the U.S. provides a supportive global backdrop – the market expectations for Mexico’s terminal rates have been joined at the hip with the U.S. Fed for some time now. The Philippines is a more difficult case – headline inflation was still accelerating (and more than expected) in November, making a strong case for more tightening in early 2023.
China Reopening
Unlike the rest of the world, China is actively easing – and November’s dismal domestic activity numbers showed why the policy stimulus had to be complemented by the zero-COVID U-turn. At the same time, weak industrial production, retail sales, and investments are clearly backward-looking. The attention now shifts to the December set of activity gauges because they come after the big policy announcements and should show an improvement (we’ve seen several “dark before dawn” reports this morning) – the market might appreciate an upside surprise. Stay tuned!
Chart at a Glance: U.S. Recession Probability – Uncomfortably High
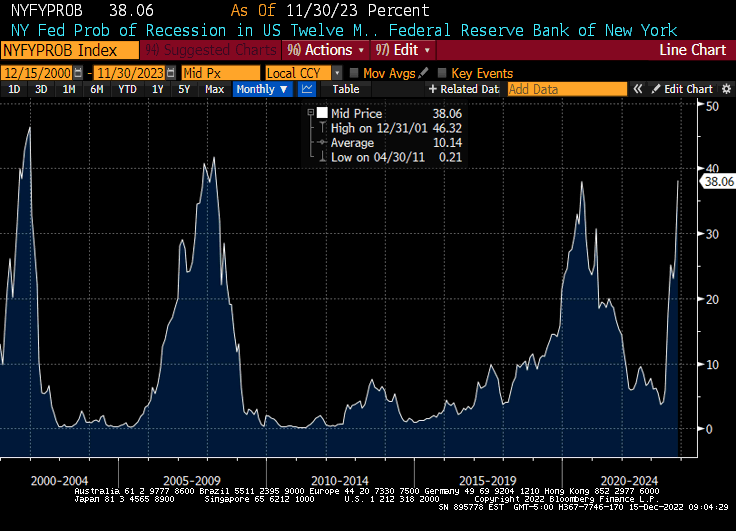
Source: Bloomberg LP.
Related Insights

Related Insights
07 April 2025
06 March 2025
13 August 2026
See how Jan van Eck's Q3 outlook can be translated into actionable ETF ideas across semiconductors, private credit, gold and bitcoin.
10 February 2026
Debasement is back in focus. Here’s what’s driving it, what could reverse it and how we’re positioning portfolios for both scenarios.
07 April 2025
Trump’s tariffs spark trade war fears, fueling market volatility, inflation risk, and recession threats. With global retaliation likely, near-term growth is clearly at risk.
06 March 2025
Trump’s tariffs, AI’s next phase, and a potential U.S. gold revaluation could shake markets—investors who stay ahead of these transitions will be best positioned.
20 February 2025
China's AI breakthrough, persistent inflation, gold’s outperformance, and rising energy demand underscore a shifting investment landscape.