Politics, Growth, Prices – Surprises Abound
24 October 2022
China Political Landscape, Growth
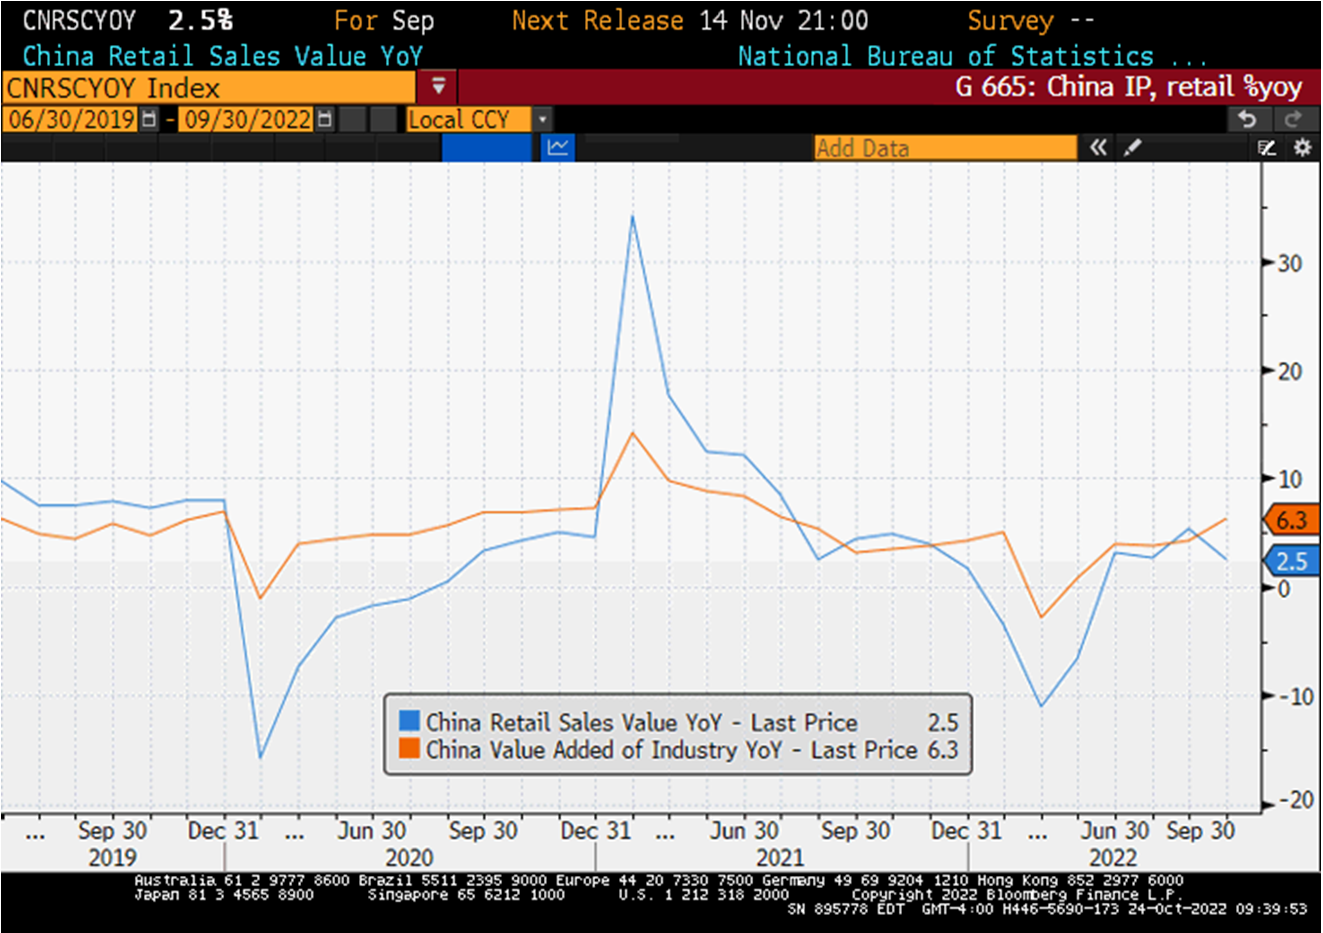
The market completely ignored China’s stronger than expected Q3 GDP print – and for a good reason. Higher-frequency domestic activity indicators were very mixed, while major changes in China’s leadership team (including the economic block) raised questions about the policy direction, as well as about political checks and balances. The next stops are (1) the Central Economic Work Conference in December, and (2) the annual meeting of the National People’s Congress and the National Committee of the Chinese People’s Political Consultative Conference (so-called “Two Sessions”) in March 2023. China’s stronger than expected but uneven GDP rebound (3.9% year-on-year in Q3) provides an interesting - and challenging - backdrop for the Central Conference, which is expected to assess progress towards annual economic targets. Above-consensus infrastructure and industrial production (see chart below) are able to lift the headline growth number, but soft consumption (retail sales), housing, and exports point to persistent headwinds, which might require more policy support.
Mexico Price Pressures
China’s surprises were not the only ones that caught the market’s attention this morning. Mexico’s bi-weekly headline inflation was lower than expected, showing tentative signs of peaking. However, core inflation continued to power ahead (8.39% year-on-year), surprisingly meaningful to the upside, and – in our opinion – making a 75bps rate hike in early November a done deal. The market sees a slower pace of tightening after the November hike (around 75bps through Q1-2023) – a reasonable expectation, given that Mexico’s real policy rate is already positive, based both on headline and expected inflation (a rarity these days).
Brazil Elections Outlook
Investors are also wondering whether there might be an election surprise in Brazil next weekend. Even though the challenger (ex-President Luiz Inácio Lula da Silva) is leading in the polls, the gap between Lula and the incumbent (President Jair Bolsonaro) continues to narrow. The runoff will have major implications for Brazil’s policy agenda, which is why economic releases – such as a wider than expected current account deficit and larger than expected foreign direct investments - are taking a back seat. Brazil’s currency and local debt outperformed most EM peers so far this year, so there is a lot to lose in the case of a policy U-turn. Stay tuned!
Chart at a Glance: China – Consumption Still Struggling
Source: Bloomberg LP
Related Insights

Related Insights
17 September 2026
17 September 2026
Rising oil prices and climbing Treasury yields pressured equities as the Fed left further tightening on the table, while Strategy led BUZZ Index gains on a bitcoin rally and commercial space names weighed on returns.
13 August 2026
See how Jan van Eck's Q3 outlook can be translated into actionable ETF ideas across semiconductors, private credit, gold and bitcoin.
17 July 2026
U.S. equities advanced despite geopolitical volatility and shifting rate expectations, but high-sentiment names lagged as investors grew more selective across AI infrastructure and growth stocks.
10 February 2026
Debasement is back in focus. Here’s what’s driving it, what could reverse it and how we’re positioning portfolios for both scenarios.
07 April 2025
Trump’s tariffs spark trade war fears, fueling market volatility, inflation risk, and recession threats. With global retaliation likely, near-term growth is clearly at risk.