EM - A Stagflation Curveball
03 April 2023
Read Time 2 MIN
Oil Production Cuts
The second quarter began with a curveball – a surprising announcement by OPEC+ (Organization of the Petroleum Exporting Countries) about production output cuts starting in May. Energy importers felt an immediate impact, and global rates initially moved higher, because the OPEC+ move has led to renewed inflation concerns. The OPEC+ supply cuts are taking place against the backdrop of the still uncertain global growth outlook, resurrecting a ghost of stagflation and adding to policy challenges faced by major central banks.
Global Growth Headwinds
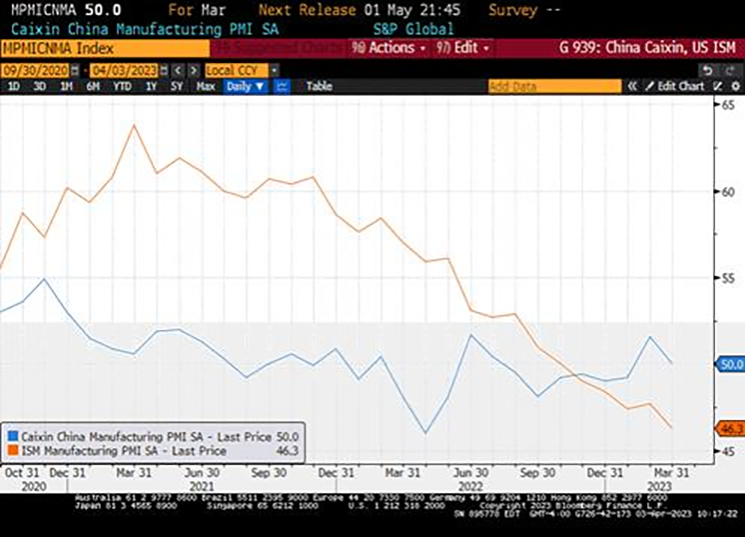
The latest activity gauges in independent global growth drivers pointed to more growth headwinds. The ISM (Institute for Supply Management) manufacturing survey in the U.S. looked ugly across the board – much weaker than expected (see chart below) and with a worrying drop in new orders. The manufacturing PMIs (Purchasing Managers Indices) in the Eurozone and the U.K. remained stuck in contraction zone. China’s surprisingly weak Caixin manufacturing PMI (50.0 – see chart below)) came on the heels of the more impressive official manufacturing and services PMI surveys, signaling that the pace of recovery in different sectors should not be taken for granted, and that smaller privately-owned companies (with a higher export component) might require additional support. Activity gauges in the rest of emerging markets (EM) were also split. Some Asian economies look strong (India, Indonesia, the Philippines, and Thailand). But others (South Korea and Malaysia) stayed “under water”. They were joined by Central European economies, South Africa, and Brazil, where the manufacturing PMI moved deeper into contraction zone (47.0).
EM Disinflation and Oil Prices
The OPEC+ production cut decision is likely to keep various central banks in EM on the cautious side, despite peaking inflation and growth headwinds. The market ignored a nice downside surprise in Indonesian inflation this morning (headline CPI dropping below 5% year-on-year, and core below 3%), and it remains to be seen whether further disinflation in South Korea and the Philippines (out later today and tomorrow) will move the “easing” dial. But EM is not a monolith, and idiosyncratic drivers should not be ignored – even on days like today. For example, Brazil’s new fiscal framework is just as important for the central bank as other inflation drivers – and a credible progress on the fiscal front can help to compensate for potential upside risks associated with higher energy prices. Stay tuned!
Chart at a Glance: Global Growth Drivers Checkup*
Source: Bloomberg LP
*MPMICNMA Index: Caixin China manufacturing index
Related Insights
IMPORTANT DEFINITIONS & DISCLOSURES
This material may only be used outside of the United States.
This is not an offer to buy or sell, or a recommendation of any offer to buy or sell any of the securities mentioned herein. Fund holdings will vary. For a complete list of holdings in VanEck Mutual Funds and VanEck ETFs, please visit our website at www.vaneck.com.
The information presented does not involve the rendering of personalized investment, financial, legal, or tax advice. Certain statements contained herein may constitute projections, forecasts and other forward looking statements, which do not reflect actual results. Information provided by third-party sources are believed to be reliable and have not been independently verified for accuracy or completeness and cannot be guaranteed. Any opinions, projections, forecasts, and forward-looking statements presented herein are valid as of the date of this communication and are subject to change without notice. The information herein represents the opinion of the author(s), but not necessarily those of VanEck.
The views contained herein are not to be taken as advice or a recommendation to buy or sell any investment in any jurisdiction, nor is it a commitment from Van Eck Associates Corporation or its subsidiaries to participate in any transactions in any companies mentioned herein. This content is published in the United States. Investors are subject to securities and tax regulations within their applicable jurisdictions that are not addressed herein.
All investing is subject to risk, including the possible loss of the money you invest. As with any investment strategy, there is no guarantee that investment objectives will be met and investors may lose money. Diversification does not ensure a profit or protect against a loss in a declining market. Past performance is no guarantee of future results.