Welcome to VanEck
Select Investor Type
13 April 2026
Read Time 5 MIN
After a volatile start to the year, several areas of the market have reset, creating more attractive opportunities in Q2. While macro conditions remain broadly supportive, the opportunity set is increasingly driven by selectivity rather than broad exposure.
The most important development this quarter is a shift in how AI is being monetized.
While early adoption was driven by consumers, the data now clearly shows that corporate America is opening its wallet. Companies are increasingly willing to invest heavily in AI due to the productivity gains it delivers, often completing tasks in minutes that previously took days.
We are seeing this firsthand at VanEck. Our own token usage has scaled to billions per day following enterprise rollouts of ChatGPT and Claude, offering a real-world example of how quickly these tools are being embedded into workflows.
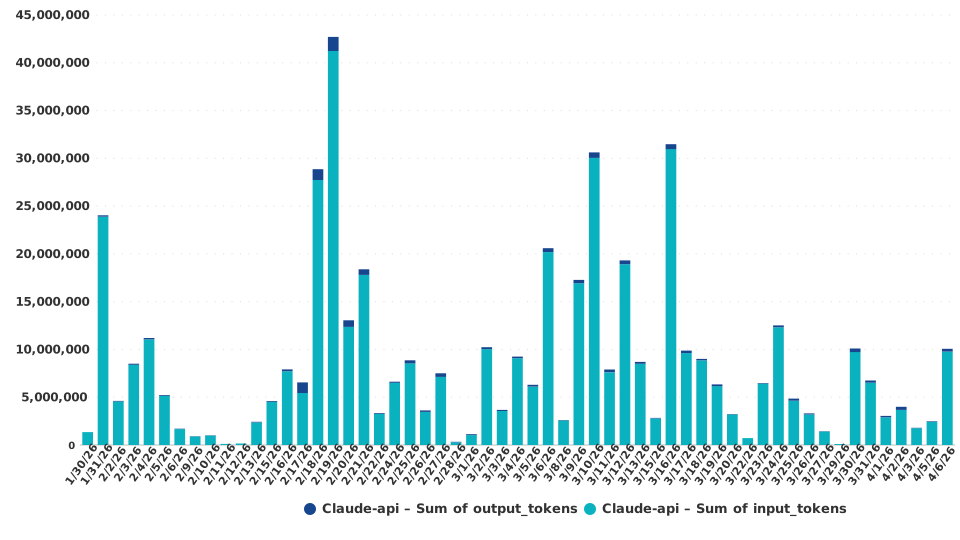
Source: VanEck. Data as of April 2026. Any projections and forward-looking statements herein are for illustrative purposes only, reflect current views as of this date, are subject to change without notice, and are not necessarily those of VanEck or its other employees. Nothing herein should be construed as investment advice, a recommendation, or a call to action. Digital assets involve significant risk and may not be suitable for all investors. Investing involves risk, including possible loss of principal. There is no guarantee any strategy will achieve its objectives, and diversification does not ensure a profit or protect against loss. Historical data only. Past performance is no guarantee of future results.
This combination of rising adoption alongside improving efficiency helps explain why total AI spending continues to grow. Even as costs per unit fall, the number of use cases and users is expanding rapidly.
Despite this, markets remain skeptical that current levels of capital expenditure can continue over the longer term. We believe that skepticism may be misplaced. Companies are unlikely to cut spending on a technology that delivers clear efficiency gains.
As a result, semiconductors remain a high-conviction area, with markets potentially underestimating the durability of AI-driven demand
Private credit continues to dominate headlines, but the underlying data tells a more measured story.
Default rates remain relatively low, and the broader U.S. economy remains resilient. Yet many business development companies (BDCs) are trading at discounts that imply significantly higher levels of stress than current fundamentals would suggest.
This disconnect creates opportunity. Publicly traded BDCs benefit from structural advantages, such as the absence of forced selling, which make them more resilient than many investors assume.
At the same time, the valuation reset has extended to the managers themselves. Firms such as Ares and Blue Owl, which previously traded at elevated multiples, now appear far more reasonably valued relative to their long-term earnings potential.
While the fiscal outlook had been improving, new spending proposals have reintroduced uncertainty. Higher deficits could place upward pressure on long-term interest rates, which would have broad implications for financial markets. This is one of the key risks we are monitoring closely.
Gold remains a critical hedge in this environment. Importantly, its long-term drivers extend beyond inflation or short-term geopolitical events. Instead, gold is supported by global wealth growth and a gradual shift away from reliance on the U.S. dollar.
Short-term volatility, such as recent selling tied to energy price shocks, does not change this longer-term trend. We continue to view gold as a strategic allocation, particularly on pullbacks.
More broadly, commodity markets are also being shaped by geopolitical developments. In the near term, shifts in the futures curve into backwardation can create additional return drivers for investors, particularly through positive roll yield. However, these dynamics are cyclical and should be understood as part of a broader allocation strategy.
India continues to offer compelling long-term growth potential, even after a period of underperformance. Structural reforms, favorable demographics and rapid digital adoption remain intact. At the same time, the market is undergoing a period of adjustment, with traditional business models being disrupted and valuations becoming more attractive.
For long-term investors, this combination of structural growth and improved entry points remains compelling.
Bitcoin’s traditional four-year cycle appears to have shifted, creating a more nuanced near-term outlook. While past cycles were marked by sharp drawdowns following halving events, recent price behavior suggests a more range-bound environment. This may reflect broader institutional participation and lower volatility.
While the near-term outlook is mixed, the long-term case for adoption remains intact. Current levels may represent a more constructive entry point for investors with a longer horizon.
Following recent volatility, the investment landscape is offering more targeted opportunities, particularly in areas where fundamentals remain intact despite sentiment weakening and valuations pulling back.
For investors, Q2 is less about broad market direction and more about identifying where resets have created more attractive entry points.
To receive more insights, sign up in our subscription center.
IMPORTANT INFORMATION
This is a marketing communication targeted to FCA regulated financial intermediaries. Retail clients should not rely on any of the information provided and should seek assistance from a financial intermediary for all investment guidance and advice.
VanEck Securities UK Limited (FRN: 1002854) is an Appointed Representative of Strata Global Limited (FRN: 563834), which is authorised and regulated by the Financial Conduct Authority (FCA) in the UK, to distribute VanEck´s products to FCA regulated firms such as financial intermediaries and Wealth Managers. The Fund is recognised in the UK under the Overseas Funds Regime but is not a UK-authorised Fund.UK investors should note that complaints in relation to the Fund cannot be referred to the Financial Ombudsman Service, and any related claims for losses will not be covered by the Financial Services Compensation Scheme.
VanEck Securities UK Limited and its associated and affiliated companies (together “VanEck”) assume no liability with regards to any investment, divestment or retention decision on the basis of this information. The views and opinions expressed are those of the author(s) but not necessarily those of VanEck. Opinions are current as of the publication date and are subject to change with market conditions. Information provided by third party sources is believed to be reliable and has not been independently verified for accuracy or completeness and cannot be guaranteed.
Investing is subject to risk, including the possible loss of principal. For any unfamiliar technical terms, please refer to ETF Glossary | VanEck.
No part of this material may be reproduced in any form, or referred to in any other publication, without express written permission of VanEck.
© VanEck Securities UK Limited
This is a marketing communication for professional investors only. Please refer to the UCITS prospectus and to the Key Investor Information Document (KIID) before making any final investment decisions.
This is a marketing communication for professional investors only. Please refer to the UCITS prospectus and to the Key Investor Information Document (KIID) before making any final investment decisions. This information originates from VanEck Securities UK Limited (FRN: 1002854), an Appointed Representative of Strata Global Limited (FRN: 563834) which is authorised and regulated by the Financial Conduct Authority in the UK. The information is intended only to provide general and preliminary information to FCA regulated firms such as Independent Financial Advisors (IFAs) and Wealth Managers. Retail clients should not rely on any of the information provided and should seek assistance from an IFA for all investment guidance and advice. VanEck Securities UK Limited and its associated and affiliated companies (together “VanEck”) assume no liability with regards to any investment, divestment or retention decision taken by the investor on the basis of this information. The views and opinions expressed are those of the author(s) but not necessarily those of VanEck. Opinions are current as of the publication date and are subject to change with market conditions. Certain statements contained herein may constitute projections, forecasts and other forward-looking statements, which do not reflect actual results. Information provided by third party sources is believed to be reliable and have not been independently verified for accuracy or completeness and cannot be guaranteed. Brokerage or transaction fees may apply.
All performance information is based on historical data and does not predict future returns. Investing is subject to risk, including the possible loss of principal.
No part of this material may be reproduced in any form, or referred to in any other publication, without express written permission of VanEck.
© VanEck Securities UK Limited
21 July 2025
21 July 2025