Welcome to VanEck
Select Investor Type
28 September 2026
When we last wrote about tokenised real-world assets in March, distributed on-chain RWAs had just crossed roughly $25 billion, a figure we called the tip of the iceberg. Six months later, the iceberg has grown faster than almost anyone expected. As of late September 2026, distributed on-chain RWA value stood above $39 billion and was closing in on the $40 billion mark, according to RWA.xyz. Perhaps more telling than the headline number: the number of tokenised-asset holders more than doubled in August, to nearly 5 million addresses by the end of September. Adoption is broadening, not just deepening.
Source: RWA.xyz as of 28/09/2026. Historical performance is no guarantee for future results.
The holder base nearly quintupled in the latest quarter, from about 1.0 million to just over 4.8 million addresses. That is by far the steepest quarterly gain in the series, and the clearest evidence that adoption is broadening.
The thesis from March holds. Set against roughly $130 trillion in global bonds, $120 trillion in equities, and $11 trillion in money-market funds, tokenisation still represents a fraction of a percent of global financial assets. The structural opportunity remains asymmetric. What has changed is the evidence that migration is underway.
Treasuries have pulled further ahead. Tokenised US Treasuries and cash-equivalent products are now the clear anchor of the market at roughly $16 billion, up from around $10 billion when we last wrote. The leaders are the names you would expect from regulated finance, each measured in billions.
The honest caveat is concentration risk. That same success is the sector’s main structural vulnerability. Depending on how you count, government-securities and cash-equivalent products account for the large majority of on-chain RWA value. This makes the headline growth number sensitive to the rate environment: were policy rates to fall sharply, the yield advantage that draws capital into tokenised Treasuries would narrow, and flows could reverse. A market that is broad on paper is still concentrated in practice.
But the base is also broadening. Tokenised equities (effectively non-existent a year ago) have become the fastest-growing newcomer, with tokenised versions of listed stocks appearing across several platforms. Private credit has settled in as a solid second category. And the institutional plumbing has moved: major market-infrastructure providers have signalled intent to integrate tokenised securities into the existing architecture of regulated markets, rather than routing around it.
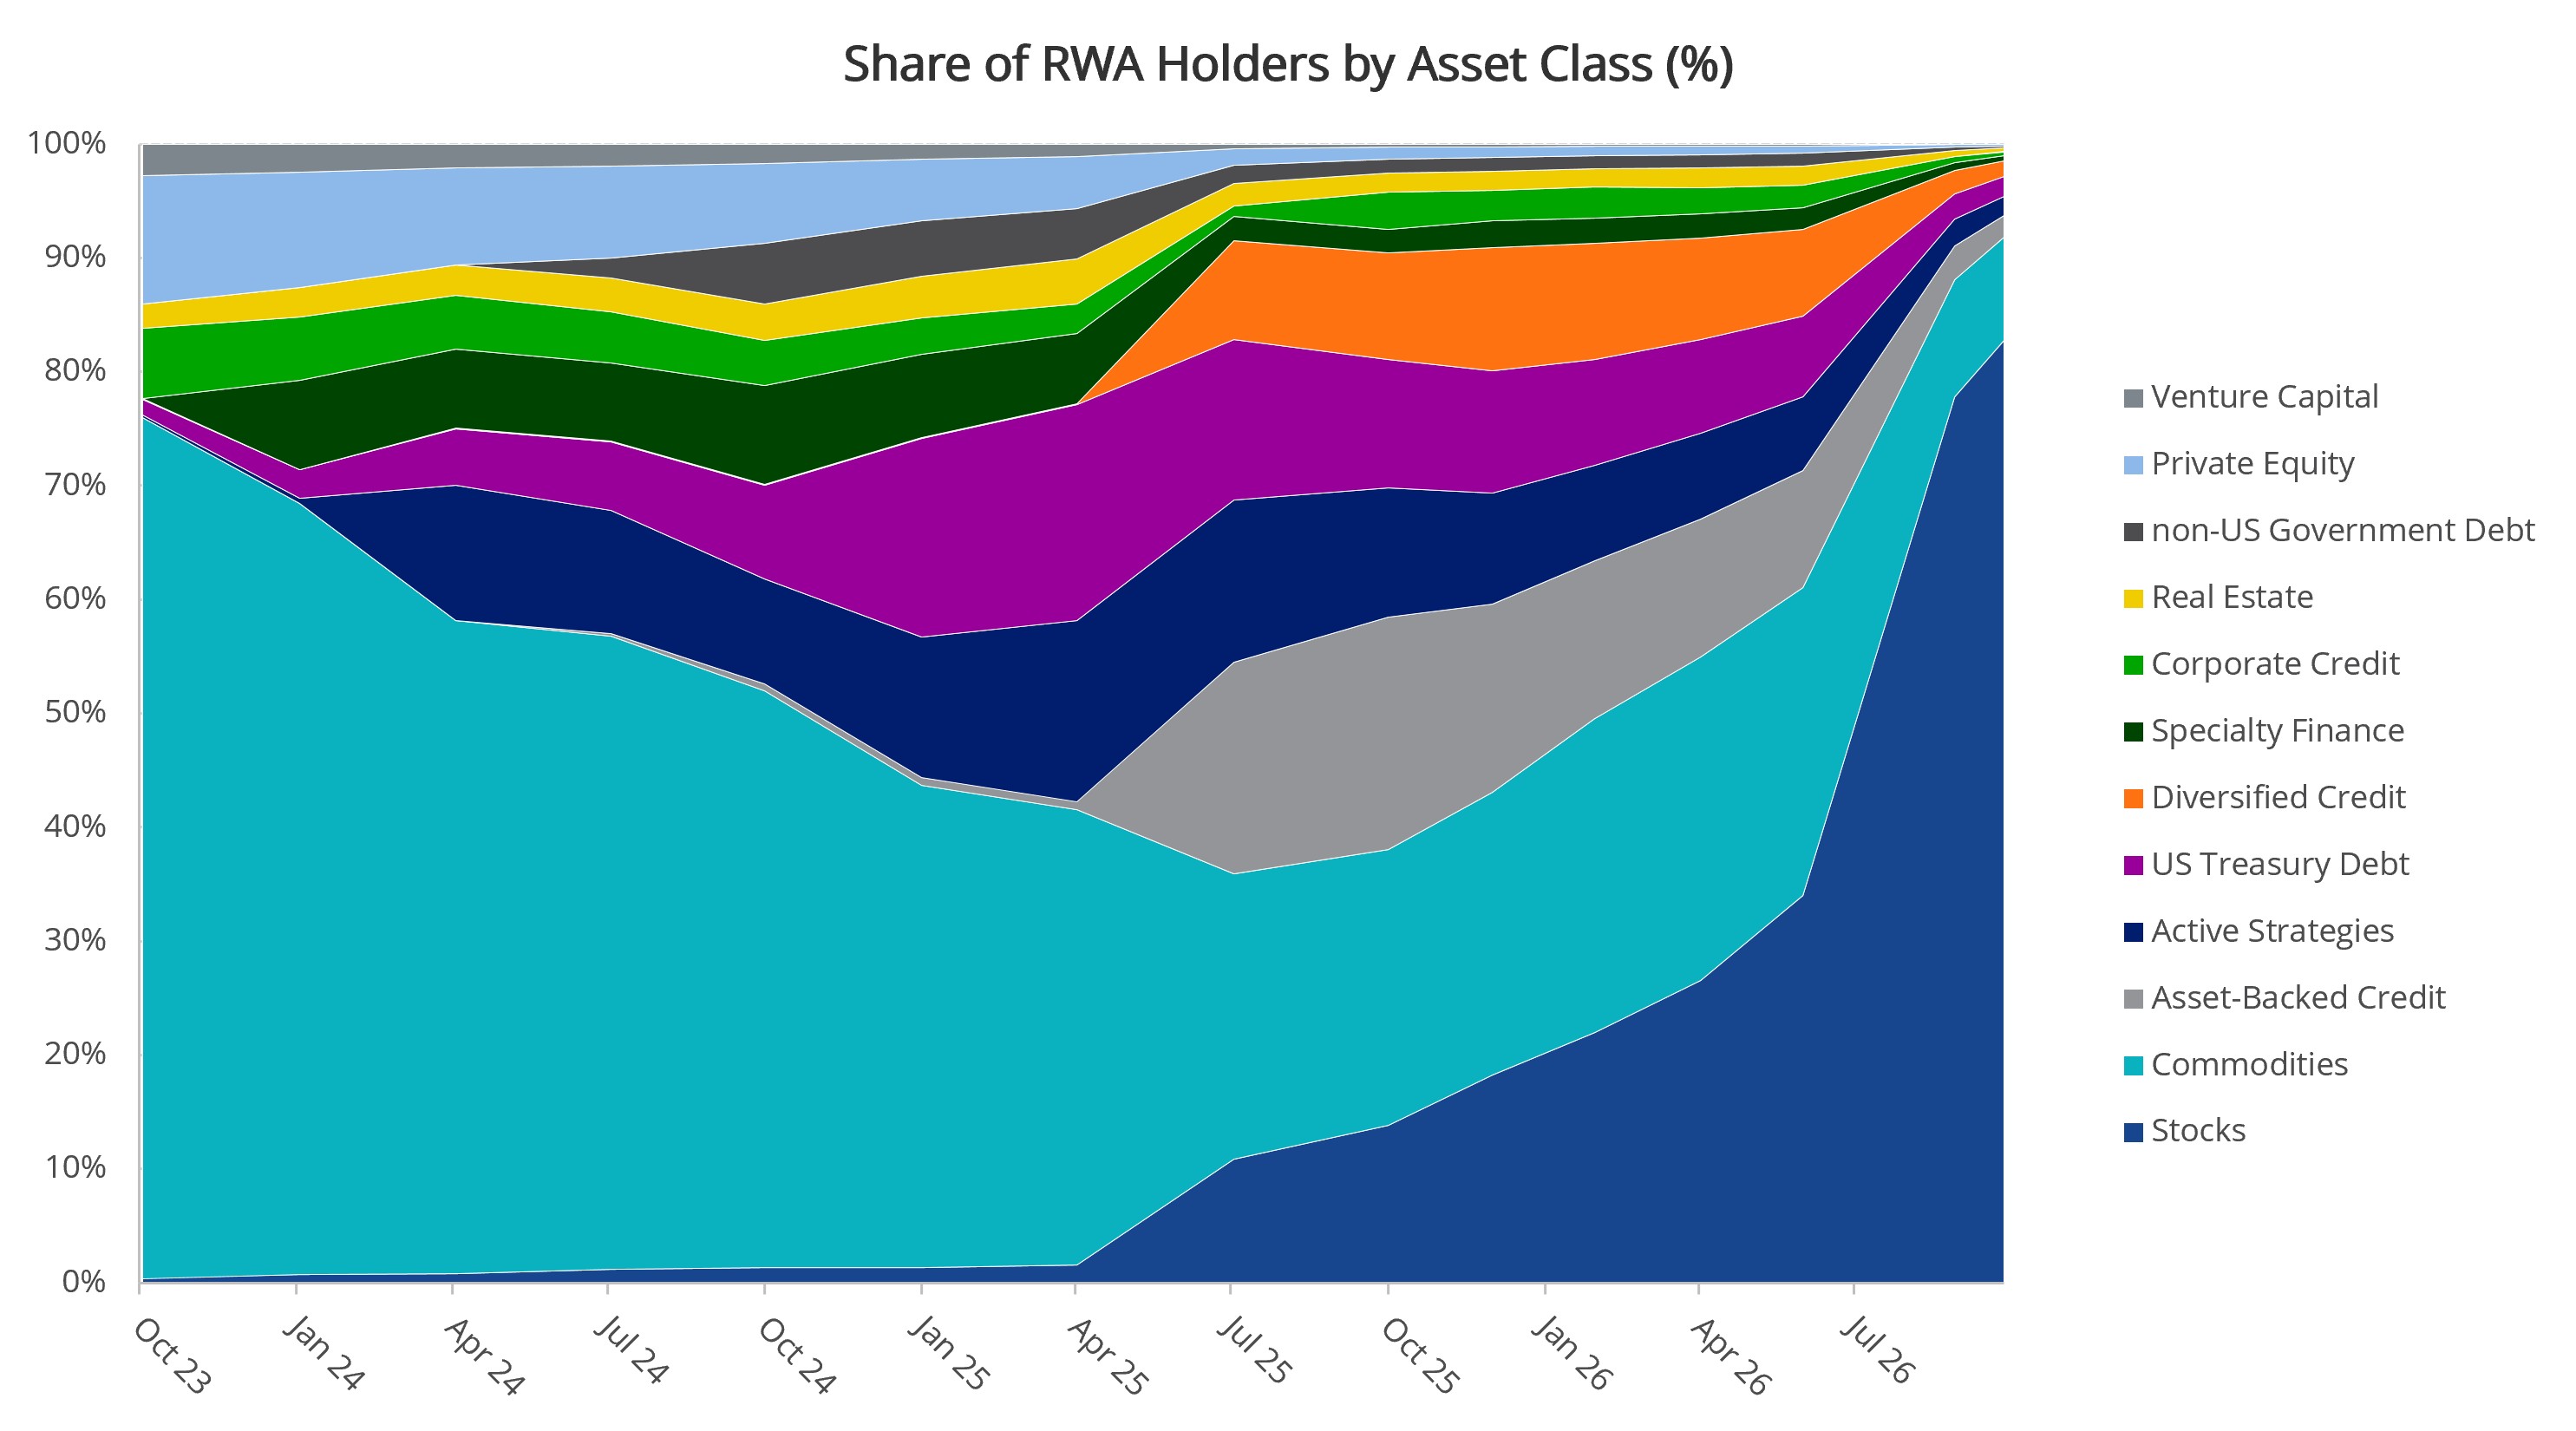
Source: RWA.xyz as of 28/09/2026. Historical performance is no guarantee for future results.
Tokenised equities now account for roughly 4.0 million of the ~4.8 million holders, up from about 200,000 two quarters earlier; the broadening base described above, even though Treasuries still dominate the market by value.
Beyond the raw growth, two developments since March reinforce the settlement-layer argument at the heart of our positioning:
Our three-layer approach for strategic allocation is unchanged; if anything, the latest data reinforces it further.
Core exposure: the settlement layer. Ethereum still hosts the majority of distributed on-chain RWA value and remains the venue of choice for flagship institutional issuance. For direct, regulated exposure to Ethereum as the dominant RWA settlement layer, the VanEck Ethereum ETN (VETH) is backed 1:1 by physically held Ether. The staking rewards* featured in the Ethereum ETN directly tap into the revenue streams of the protocol (which increasingly includes transaction fees from inssuance, management and trading of tokenised RWAs). *Staking rewards are not guaranteed.
Risk: Ether is highly volatile; regulatory, technological, or sentiment shifts could adversely affect its price. VETH investors are exposed to the full price volatility of Ether.
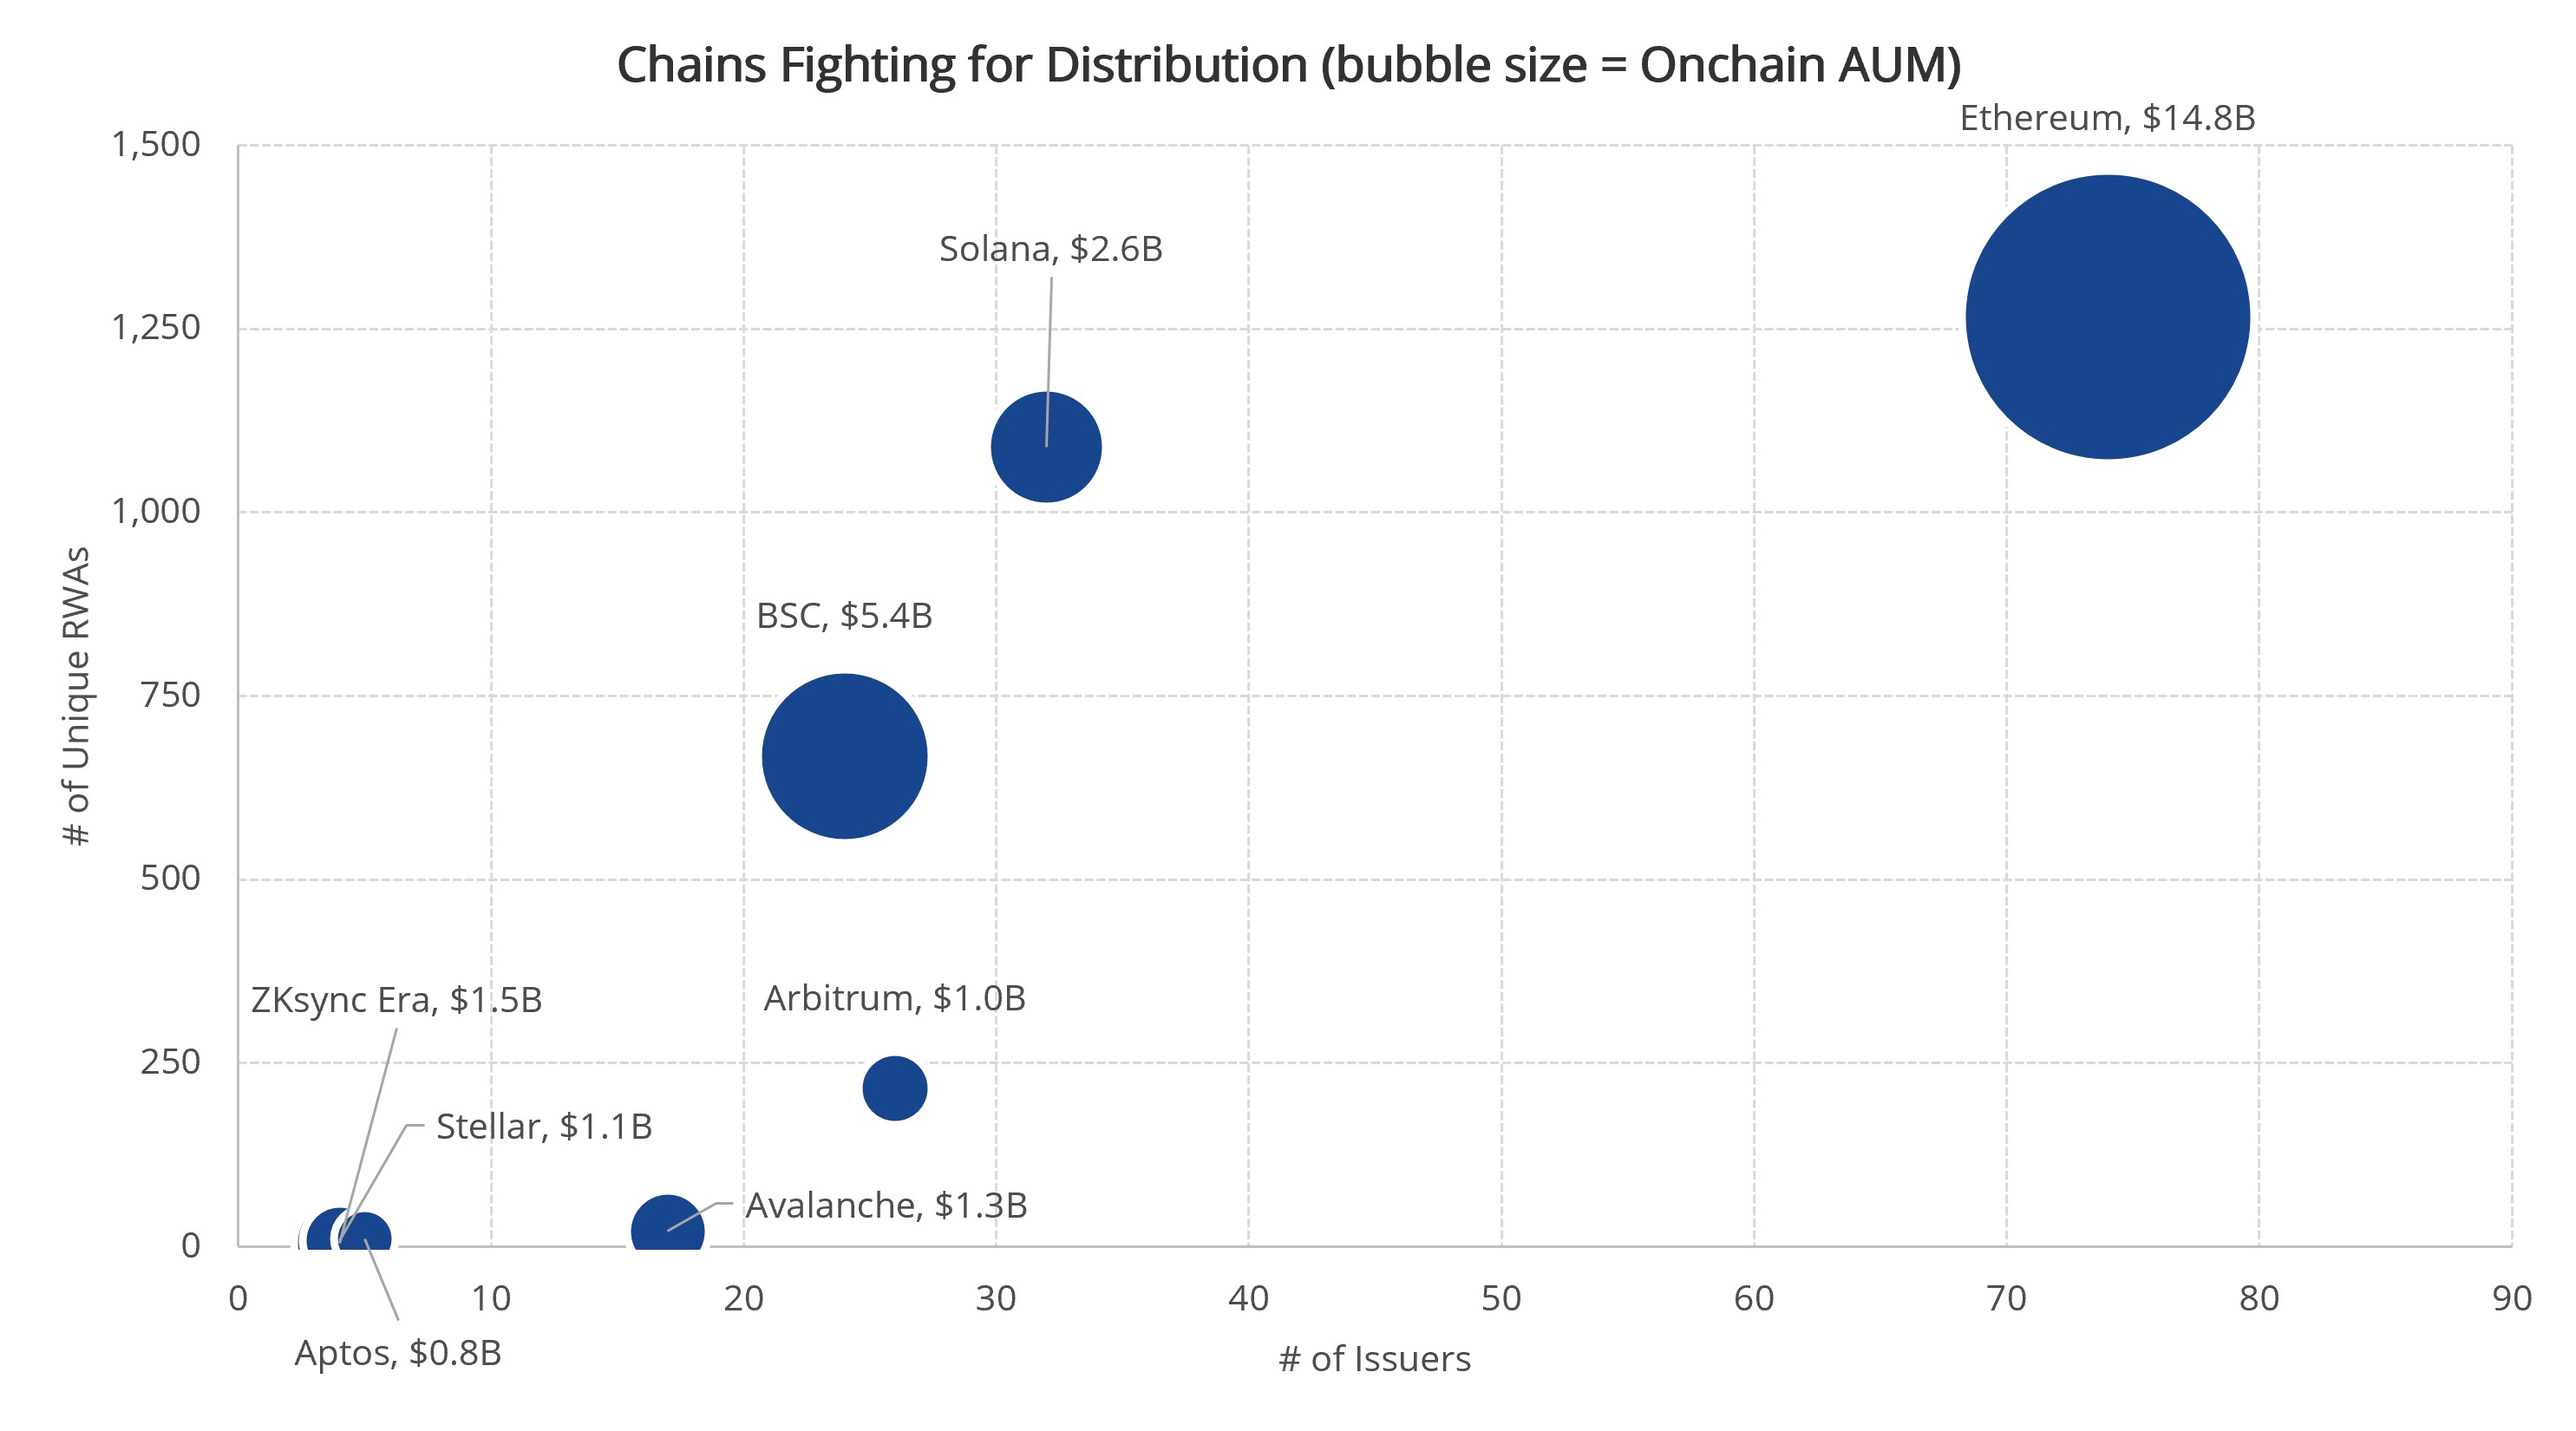
Source: Defillama as of 28/09/2026. Historical performance is no guarantee for future results.
Ethereum still carries the largest distributed market cap, but issuers and unique assets are spreading across BSC, Stellar, Solana and others, the single-chain concentration question that the diversified-platform allocation below is meant to address.
Diversified platform exposure. For investors concerned about single-chain concentration, the VanEck Crypto Leaders ETN (VTOP) and VanEck Smart Contract Leaders ETN (VSMA) provide basket exposure across the smart-contract platforms competing for RWA issuance and settlement flows.
Risk: Diversification does not eliminate risk; individual components may be volatile, illiquid, or subject to regulatory uncertainty.
Infrastructure layer: data and verification. Tokenised assets depend on oracles for price feeds, NAV updates, and proof-of-reserve checks. Exposure to this often-overlooked layer is available via the VanEck Chainlink ETN (VLNK) and VanEck Pyth ETN (VPYT).
Risk: Oracle networks are an early-stage segment; LINK and PYTH can be highly volatile and face competition and regulatory risk.
In March the story was a milestone; in September it is a clear trajectory. The market has grown by roughly half in six months, the holder base is expanding quickly, and the institutional rails are being laid. The concentration in Treasuries is a genuine caveat and a rate-sensitivity risk worth flagging. But the direction of travel (traditional finance migrating, gradually, onto regulated on-chain infrastructure) is clearer than it was six months ago. The iceberg is still mostly below the surface.
This is not financial research but the opinion of the author of the article. We publish this information to inform and educate about recent market developments and technological updates, not to give any recommendation for certain products or projects. The selection of articles should therefore not be understood as financial advice or recommendation for any specific product and/or digital asset. We may occasionally include analysis of past market, network performance expectations and/or on-chain performance. Historical performance is not indicative for future returns.
IMPORTANT INFORMATION
For informational and advertising purposes only.
This information originates from VanEck (Europe) GmbH, Kreuznacher Strasse 30, 60486 Frankfurt am Main, Deutschland and VanEck Switzerland AG, Genferstrasse 21, 8002 Zurich, Switzerland.
It is intended only to provide general and preliminary information to investors and shall not be construed as investment, legal or tax advice. VanEck (Europe) GmbH and its associated and affiliated companies (together “VanEck”) assume no liability with regards to any investment, divestment or retention decision taken by the investor on the basis of this information. Views and opinions expressed are current as of the date of this information and are subject to change with market conditions. Certain statements contained herein may constitute projections, forecasts and other forward looking statements, which do not reflect actual results. VanEck makes no representation or warranty, express or implied regarding the advisability of investing in securities or digital assets generally or in the product mentioned in this information (the “Product”) or the ability of the underlying Index to track the performance of the relevant digital assets market.
Investing is subject to risk, including the possible loss of principal up to the entire invested amount and the extreme volatility that ETNs experience. You must read the prospectus and KID before investing, in order to fully understand the potential risks and rewards associated with the decision to invest in the Product. The approved Prospectus is available at www.vaneck.com. Please note that the approval of the prospectus should not be understood as an endorsement of the Products offered or admitted to trading on a regulated market.
The underlying Index is the exclusive property of MarketVector Indexes GmbH. MarketVector uses its best efforts to ensure that the Index is calculated correctly.
All indices are unmanaged and include the reinvestment of all returns but do not reflect the payment of transactions costs or expenses that are typically associated with digital assets portfolios. Indices were selected for illustrative purposes only and are not securities in which investments can be made. The returns of actual accounts investing in digital assets are likely to differ from the performance of each corresponding index. In addition, the returns of accounts will vary from the performance of the indices for a variety of reasons, including timing and individual account objectives and restrictions. Accordingly, there can be no assurance that the benefits and risk/return profile of the indices shown would be similar to those of actual accounts managed. Performance is shown for the stated time period only.
Investing is subject to risk, including the possible loss of principal up to the entire invested amount and the extreme volatility that ETNs experience. You must read the prospectus and KID before investing, in order to fully understand the potential risks and rewards associated with the decision to invest in the Product. The approved Prospectus is available at www.vaneck.com. Please note that the approval of the prospectus should not be understood as an endorsement of the Products offered or admitted to trading on a regulated market.
Performance quoted represents past performance, which is no guarantee of future results and which may be lower or higher than current performance.
Current performance may be lower or higher than average annual returns shown. Performance shows 12 month performance to the most recent Quarter end for each of the last 5yrs where available. E.g. ‘1st year’ shows the most recent of these 12-month periods and ‘2nd year’ shows the previous 12 month period and so on. Performance data is displayed in Base Currency terms, with net income reinvested, net of fees. Brokerage or transaction fees will apply. Investment return and the principal value of an investment will fluctuate. Notes may be worth more or less than their original cost when redeemed.
Index returns are not ETN returns and do not reflect any management fees or brokerage expenses. An index’s performance is not illustrative of the ETN’s performance. Investors cannot invest directly in the Index. Indices are not securities in which investments can be made. No part of this material may be reproduced in any form, or referred to in any other publication, without express written permission of VanEck.
© VanEck (Europe) GmbH / © VanEck Switzerland AG
This is a marketing communication. Please refer to the prospectus of the UCITS and to the KID before making any final investment decisions.
This information originates from VanEck (Europe) GmbH, which has been appointed as distributor of VanEck products in Europe by the Management Company VanEck Asset Management B.V., incorporated under Dutch law and registered with the Dutch Authority for the Financial Markets (AFM). VanEck (Europe) GmbH with registered address at Kreuznacher Str. 30, 60486 Frankfurt, Germany, is a financial services provider regulated by the Federal Financial Supervisory Authority in Germany (BaFin).
The information is intended only to provide general and preliminary information to investors and shall not be construed as investment, legal or tax advice VanEck (Europe) GmbH, VanEck Switzerland AG, VanEck Securities UK Limited and their associated and affiliated companies (together “VanEck”) assume no liability with regards to any investment, divestment or retention decision taken by the investor on the basis of this information. The views and opinions expressed are those of the author(s) but not necessarily those of VanEck. Opinions are current as of the publication date and are subject to change with market conditions. Certain statements contained herein may constitute projections, forecasts and other forward-looking statements, which do not reflect actual results. Information provided by third party sources is believed to be reliable and have not been independently verified for accuracy or completeness and cannot be guaranteed. Brokerage or transaction fees may apply.
All performance information is based on historical data and does not predict future returns. Investing is subject to risk, including the possible loss of principal.
No part of this material may be reproduced in any form, or referred to in any other publication, without express written permission of VanEck.
© VanEck (Europe) GmbH / VanEck Asset Management B.V.
24 September 2026
24 September 2026