EM Hawks Strike Back
June 28, 2022
Read Time 2 MIN
EM Rate Hikes – Doing the Right Thing
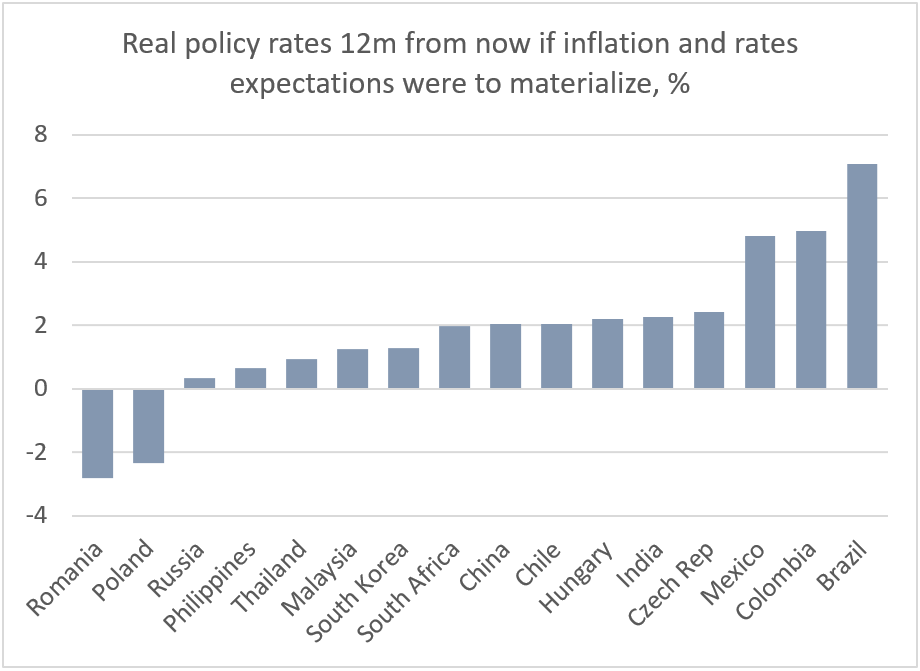
Some emerging markets (EM) central banks might be contemplating a slower pace of tightening, but many continue to act decisively, hiking higher and more aggressively in order to reduce inflation pressures and anchor expectations. Hungary’s surprising 185bps rate hike this morning (vs +50bps consensus) falls into this category. The move ended Hungary’s interest rate corridor, simplifying the policy framework. In addition, Hungary’s 12-month ahead real policy rate is now well in positive territory – together with the majority of EMs (see chart below). This is a much better picture than several months ago, but the chart also shows that central banks in Poland and Romania have more to do to address double-digit inflation. One of Poland’s monetary policy council members called for accelerating the pace of hikes to at least 100bps in July from 75bps in June.
DM Rate Expectations – More Growth Concerns
Back in developed markets (DM), the market scaled back its expectations for the next rate hike in the U.S. (now under 70bps) – today’s below-consensus Conference Board Consumer Confidence Index comes on the heels of the similarly weak University of Michigan survey, and is likely to reinforce concerns that the U.S. Federal Reserve (Fed) is hiking into the recession. The Eurozone is still expected to begin its liftoff with +30bps rate in next month, followed by +50bps in September. However, today’s extremely weak consumer confidence prints in Germany and France should raise more doubts about the region’s near-term growth prospects – some analysts are using a term “slowflation” (a combination of weak growth and high inflation) to describe what’s going on.
China Zero-COVID Policy, Growth
This backdrop helps to explain why the market reacted positively to China’s announcement about easing some COVID restrictions, including shorter quarantine for visitors. China is one of the world’s independent growth drivers – the only one in EM – and the zero-COVID policy was among the key factors behind the on-going downgrade of China’s 2022 GDP forecast, which now stands at 4.18% (vs. the official target of about 5.5%). An upside surprise in China’s June activity gauges (out on Wednesday evening) might not lead to an immediate growth upgrade, but it should provide reassurances that the worst is behind us. Stay tuned!
Chart at a Glance: EM Real Policy Rates Look More Reassuring
Source: VanEck Research; Bloomberg LP
