Disinflation, Pivots – Easy Does It?
December 12, 2022
Read Time 2 MIN
FED Pivot Prospects
This week, all eyes are on the U.S. inflation print and the Federal Reserve’s (Fed) rate-setting meeting. The consensus view is that further disinflation will allow the Fed to slow the pace of rate hikes to 50bps, with this cycle’s terminal rate peaking at 5%. Fed Funds Futures continue to price in 40-50bps of rate cuts in the second half of 2023, which many consider a stretch, given that U.S. inflation might still be above 3% by the end of the next year (if the current consensus forecast were to materialize).
EM Disinflation, Rates
Meanwhile, emerging markets (EM) inflation releases continue to send dovish signals, starting with a sizable downside surprise in India, where headline inflation actually moved back to the target range in November (5.88% year-on-year). The Indian central bank had just delivered a 35bps rate hike, and today’s print raises a possibility of a pause at the next meeting in February. Headline inflation in the Czech Republic exceeded expectations, accelerating to 16.2% year-on-year, but it was well below the peak, and core price pressures are moderating. Against this backdrop, there is no reason for the central bank to get alarmed. The market expectations that the policy pause will be extended into Q1-2023 look reasonable, albeit the pace of subsequent easing will depend on the growth trajectory and the disinflation progress.
China Stimulus
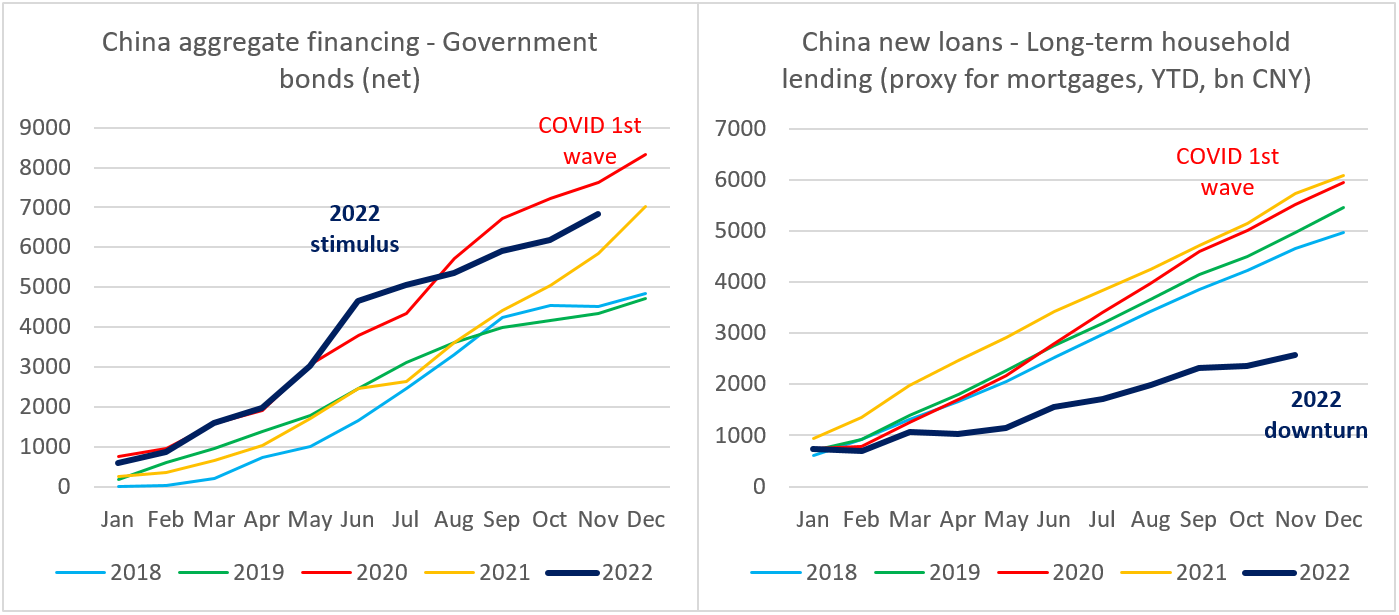
China’s inflation continued to moderate in November, but this should be expected to change if reopening gains pace. November’s credit aggregates also showed that the latest policy shift gave a small sequential boost to corporate and household lending (including mortgages). However, the improvement is very gradual – both new loans and aggregate financing surprised to the downside – and it remains to be seen whether (or when) authorities can stop relying on government bond issuance to prop up growth (see chart below), raising a bunch of concerns about leverage (again). Stay tuned!
Chart at a Glance: China Credit Growth – Different Dynamics
Source: Bloomberg LP
