VEFA Rebalance: Analyst Conviction Shifts to Industrials
September 18, 2026
Read Time 11 min
Key Takeaways
- Industrials led all sectors in net positions added with +5.6% portfolio weight, driven by European rearmament and capex recovery.
- Japan swung from last quarter's biggest reduction to this quarter's biggest addition on AI chip demand and rate normalization.
- IT services faced the sharpest cuts, with SAP, Capgemini, and NEC removed as software analyst sentiment weakened.
- Energy, last quarter's dominant theme, saw no new additions, signaling a pause in the crude-driven upgrade cycle from the prior quarter.
The VanEck MSCI EAFE Analyst Sentiment ETF (VEFA) tracks the MSCI EAFE Analyst Sentiment Select Index, which completed its quarterly rebalance on September 1. The index systematically tilts toward stocks where sell-side analysts are most actively raising expectations across earnings estimates, price targets, sales forecasts, cash flow projections and ratings changes.
Since VEFA’s launch, the index has outperformed the MSCI EAFE parent and all major factor indices through August 31. Over the most recent quarter, performance was again ahead of the benchmark and most factors, with Value the only factor to edge ahead. Index performance does not represent fund performance and does not reflect management fees or transaction costs.
| 6/1/2026 - 8/31/2026 | 4/2/2026 - 8/31/2026* | |
| MSCI EAFE Analyst Sentiment Select Index | 5.95 | 16.53 |
| MSCI EAFE Growth Index | 1.64 | 10.55 |
| MSCI EAFE Value Index | 6.52 | 11.68 |
| MSCI EAFE Momentum Index | 0.63 | 8.49 |
| MSCI EAFE Index | 4.06 | 11.02 |
*VEFA’s inception date is 4/2/26
Source: Morningstar as of 8/31/2026. Past performance is no guarantee of future results. Index performance is not representative of fund performance. It is not possible to invest directly in an index.
What Changed in VEFA’s September Rebalance?
Industrials were the dominant story of the quarter, producing the largest single-sector net addition at over 5.6%. Rolls-Royce, ASSA ABLOY, Atlas Copco, Legrand, A.P. Moller-Maersk and VAT Group all entered the index. European rearmament drove broad earnings upgrades across the defense industrial base, with Rolls-Royce seeing a full-year guidance raise and a return to dividends. Atlas Copco, ASSA ABLOY, and Legrand reflect a broader European capex recovery, while VAT Group, a Swiss vacuum valve maker supplying semiconductor fabs, captures a separate AI-driven equipment cycle.
Japan saw the largest net buying of any country, swinging from last quarter’s biggest reduction to this quarter’s biggest addition. Analysts previously cut Japanese consumer and industrial names on import cost pressures from elevated crude prices. Those pressures have been replaced by two upgrade drivers: AI semiconductor demand and rate normalization. Tokyo Electron and Keyence entered on analyst upgrades tied to accelerating global fab equipment spending. Mitsubishi UFJ Financial Group entered as the largest single addition this rebalance, with the Bank of Japan’s rate increases driving record profits and a upgrade cycle across Japanese financials.
On the selling side, IT services and software were the most thematically coherent reductions. SAP, Capgemini, NEC and Logitech were all removed as analyst conviction weakened across enterprise software and IT services. SAP faced a wave of downgrades tied to concerns about slower-than-expected AI product rollout. Capgemini was caught in a broader pullback in IT services sentiment following a major peer’s guidance cut. The pattern is consistent: near-term revenue visibility softened and the analyst revision environment deteriorated.
Energy, the dominant theme of the first rebalance, saw no new names entering the index. Santos was removed, a signal that the analyst upgrade cycle driven by elevated crude prices has paused.
Australia saw its second consecutive reduction. Chinese steel demand weakness continued to weigh on materials names, with Rio Tinto facing analyst downgrades on iron ore price concerns. The index deleted Rio Tinto Ltd but still holds Rio Tinto PLC. Commonwealth Bank and Santos were removed on name-specific headwinds. As with last quarter, these are distinct stories rather than a single macro driver.
By Sector
| Sector | Added (%) | Removed (%) | Net (%) |
| Industrials | 6.39 | -0.74 | 5.64 |
| Financials | 3.18 | -4.34 | -1.16 |
| Information Technology | 2.77 | -2.95 | -0.18 |
| Communication Services | 1.58 | -1.37 | 0.21 |
| Utilities | 0.64 | 0 | 0.64 |
| Consumer Staples | 0.60 | 0 | 0.60 |
| Health Care | 0.88 | -0.96 | -0.08 |
| Materials | 0.24 | -1.52 | -1.28 |
| Energy | 0 | -0.42 | -0.42 |
| Real Estate | 0 | -0.61 | -0.61 |
By Country
| Country | Added (%) | Removed (%) | Net (%) |
| Japan | 6.07 | -2.88 | 3.20 |
| Sweden | 2.87 | 0 | 2.87 |
| France | 2.66 | -0.84 | 1.83 |
| Switzerland | 0.89 | -0.32 | 0.57 |
| Denmark | 0.49 | 0 | 0.49 |
| Germany | 0.60 | -1.37 | -0.77 |
| Spain | 0.64 | -1.21 | -0.56 |
| United Kingdom | 1.48 | -1.92 | -0.43 |
| Italy | 0.33 | -0.51 | -0.19 |
| Ireland | 0 | -0.49 | -0.49 |
| Netherlands | 0 | -0.49 | -0.49 |
| Australia | 0.24 | -2.90 | -2.66 |
Source: VanEck and MSCI. Data reflects the September 1 rebalance. Holdings and allocations are subject to change and are not recommendations to buy or sell any security.
Top 3 Additions to VEFA
Mitsubishi UFJ Financial Group (Japan, Financials, 2.2% Index weight): As the Bank of Japan continued raising rates toward levels not seen in decades, Japan’s major banks have seen a sustained upgrade cycle driven by improving lending margins and bond income. MUFG, one of the largest financial names in the EAFE universe, saw analyst conviction build throughout the quarter.
Orange (France, Communication Services, +1.5% Index weight): French telecom operator Orange saw improving analyst sentiment through the quarter as its fiber rollout generated better-than-expected revenue momentum and cost discipline drove margin improvement. Analysts revised estimates higher on improving earnings visibility.
ASSA ABLOY (Sweden, Industrials, +1.5% Index weight): ASSA ABLOY, the Swedish access control and door opening specialist, entered on analyst upgrades tied to recovering commercial construction activity across Europe and accelerating demand for smart access systems. It sits in the same industrials sector bucket as Rolls-Royce and Atlas Copco but represents a more domestically driven European demand story.
Recommended subscription
Top 3 Removals from VEFA
Lloyds Banking Group (United Kingdom, Financials): Lloyds faced a run of analyst downgrades as revenue came in below expectations and concerns grew around its domestic mortgage business. The contrast with MUFG illustrates how the strategy reads sentiment at the individual stock level.
SAP (Germany, Information Technology): SAP was removed following a series of analyst downgrades tied to concerns that its AI product rollout was behind schedule. A broader softening in European software sentiment compounded the stock-specific pressure, weakening SAP’s revision signal.
BBVA (Spain, Financials): Analyst conviction for BBVA weakened, driven by uncertainty around its protracted takeover attempt for Sabadell and concerns about earnings volatility from its emerging market exposure in Mexico and Turkey. The revision signal deteriorated relative to other European financials remaining in the index.
How VEFA Responds as Market Drivers Shift
The shift from last quarter’s rebalance to this one is instructive. Three months ago, the portfolio moved decisively in one direction on one driver. This quarter is more layered: European industrial capex, Japanese semiconductor equipment, Bank of Japan normalization, and the continued unwind of China-exposed commodity names are four distinct signals. The strategy does not adjudicate between them. It reads analyst conviction across every name in the EAFE universe and tilts the portfolio accordingly.
How VEFA Is Positioned vs. the Benchmark
The charts below show VEFA’s active weights relative to the MSCI EAFE Index as of September 1.
Sector Weighting Differences vs. MSCI EAFE
Value by Sector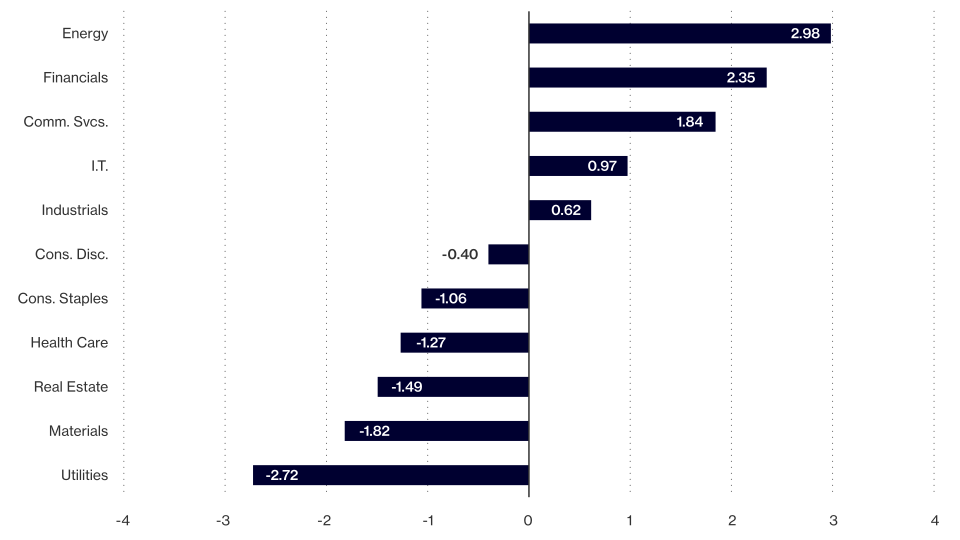
Source: VanEck and MSCI. Data as of 9/1/2026.
Energy remains VEFA’s largest sector overweight despite this quarter’s pause in energy additions. The Q1 additions (BP, Shell, ENI and Equinor) are still in the portfolio; the rebalance trimmed the momentum rather than reversed it. Financials and Communication Services are also overweights, while Utilities is the largest underweight by a significant margin.
Ten Largest Country Weighting Differences vs. MSCI EAFE
Values by Country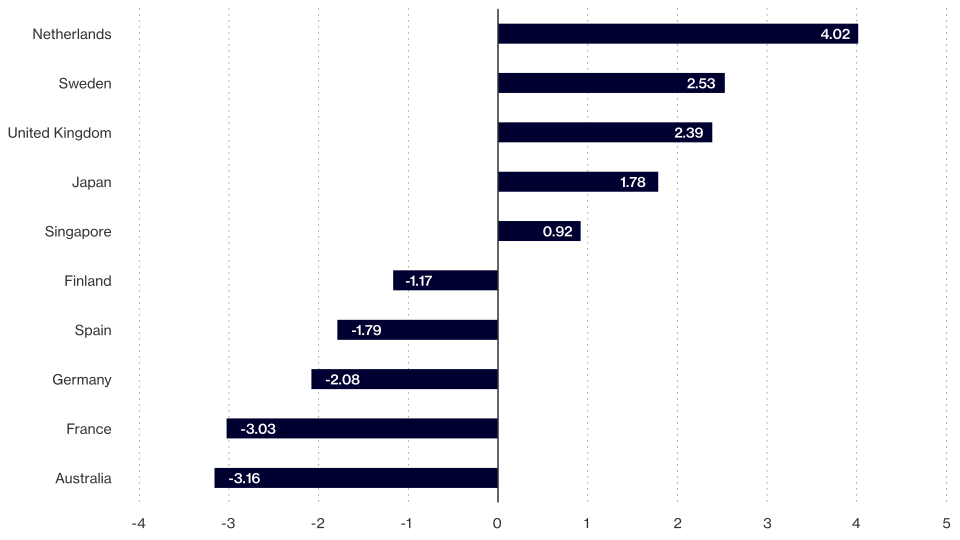
Source: VanEck and MSCI. Data as of 9/1/2026.
The Netherlands is VEFA’s largest overweight, driven by ASML and ING Groep. Sweden and the United Kingdom are also meaningfully overweight. Australia is the largest underweight at approximately -3.2%. VEFA holds only three of the Australian names (Macquarie Group, BHP, and PLS Group) in the benchmark. The underweight is primarily driven by the absence of financials and materials names. The Australia underweight is the sum of those individual signals, not a call on the country.
Across both sectors and countries, the active positions are deliberate but modest, consistent with the strategy’s objective of staying below 4% tracking error relative to the parent benchmark.
Index Rebalance Appendix
Additions
| Security | Country | Sector | Weight Change (%) |
| Mitsubishi UFJ Fin Grp | Japan | Financials | 2.12 |
| Orange | France | Communication Services | 1.58 |
| ASSA ABLOY B | Sweden | Industrials | 1.49 |
| Rolls-Royce Group | United Kingdom | Industrials | 1.48 |
| Atlas Copco A | Sweden | Industrials | 1.39 |
| Tokyo Electron | Japan | Information Technology | 1.13 |
| Legrand | France | Industrials | 1.08 |
| Keyence Corp | Japan | Information Technology | 1.06 |
| Naturgy Energy Group | Spain | Utilities | 0.64 |
| Henkel Vorzug | Germany | Consumer Staples | 0.60 |
| Kyocera Corp | Japan | Information Technology | 0.58 |
| Astellas Pharma | Japan | Health Care | 0.57 |
| AP Moller-Maersk B | Denmark | Industrials | 0.49 |
| VAT Group | Switzerland | Industrials | 0.46 |
| Julius Baer Group | Switzerland | Financials | 0.43 |
| Poste Italiane | Italy | Financials | 0.33 |
| Shionogi & Co | Japan | Health Care | 0.31 |
| Japan Exchange Group | Japan | Financials | 0.31 |
| PLS Group | Australia | Materials | 0.24 |
Deletions
| Security | Country | Sector | Weight Change (%) |
| Lloyds Banking Group | United Kingdom | Financials | -1.66 |
| SAP | Germany | Information Technology | -1.37 |
| BBVA | Spain | Financials | -1.21 |
| Rio Tinto Ltd | Australia | Materials | -1.10 |
| Commonwealth Bank of Aus | Australia | Financials | -0.96 |
| Capgemini | France | Information Technology | -0.84 |
| NTT Corp | Japan | Communication Services | -0.76 |
| Nintendo Co | Japan | Communication Services | -0.61 |
| BPER Banca | Italy | Financials | -0.51 |
| Ryanair Holdings | Ireland | Industrials | -0.49 |
| Koninklijke Philips | Netherlands | Health Care | -0.49 |
| Daiichi Sankyo Co | Japan | Health Care | -0.48 |
| Santos | Australia | Energy | -0.42 |
| Evolution Mining | Australia | Materials | -0.42 |
| NEC Corp | Japan | Information Technology | -0.42 |
| Daiwa House Industry | Japan | Real Estate | -0.34 |
| Logitech | Switzerland | Information Technology | -0.32 |
| Sumitomo Realty & Dev Co | Japan | Real Estate | -0.27 |
| Rentokil Initial | United Kingdom | Industrials | -0.25 |
Source: VanEck and MSCI. Data reflects the September 1 rebalance. Holdings and allocations are subject to change and are not recommendations to buy or sell any security.
VEFA | VanEck MSCI EAFE Analyst Sentiment ETF
To receive more Emerging Markets Equity insights, sign up in our subscription center.

Important Disclosures
This is not an offer to buy or sell, or a recommendation to buy or sell any of the securities, financial instruments or digital assets mentioned herein. The information presented does not involve the rendering of personalized investment, financial, legal, tax advice, or any call to action. Certain statements contained herein may constitute projections, forecasts and other forward-looking statements, which do not reflect actual results, are for illustrative purposes only, are valid as of the date of this communication, and are subject to change without notice. Actual future performance of any assets or industries mentioned are unknown. Information provided by third party sources are believed to be reliable and have not been independently verified for accuracy or completeness and cannot be guaranteed. VanEck does not guarantee the accuracy of third party data. The information herein represents the opinion of the author(s), but not necessarily those of VanEck or its other employees.
MSCI EAFE Index captures large and mid cap representation across developed markets around the world, excluding the U.S. and Canada.
MSCI EAFE Analyst Sentiment Select Index is based on the MSCI EAFE Index, its parent index. The index uses an optimization process that aims to maximize the exposure to the Analyst Sentiment factor, while controlling for active risk, active specific risk and net ex-ante beta relative to the parent index.
MSCI EAFE Growth Index is based on the MSCI EAFE index, its parent index, and tracks large- and mid-cap growth stocks across developed markets, excluding the U.S. and Canada.
MSCI EAFE Value Index is based on the MSCI EAFE index, its parent index, and tracks large- and mid-cap value stocks across developed markets, excluding the U.S. and Canada.
MSCI EAFE Momentum Index is based on the MSCI EAFE index, its parent index, and tracks large- and mid-cap stocks with high price momentum across developed markets, excluding the U.S. and Canada.
Holdings will vary for the VEFA and its corresponding Index. Visit vaneck.com/vefa for a complete list of holdings in the ETF.
Index returns are not Fund returns and do not reflect any management fees or brokerage expenses. Certain indices may take into account withholding taxes. Investors can not invest directly in the Index. Returns for actual Fund investors may differ from what is shown because of differences in timing, the amount invested and fees and expenses. Index returns assume that dividends have been reinvested. Past performance is no guarantee of future results.
An investment in the Fund may be subject to risks which include, among others, risks related to investing in foreign securities, foreign currency, financials sector, industrials sector, health care sector, special risk considerations of investing in European, Japanese and United Kingdom issuers, depositary receipts, equity securities, issuer-specific changes, medium- and large-capitalization companies, market, operational, index tracking, authorized participant concentration, new fund, no guarantee of active trading market, trading issues, passive management, fund shares trading, premium/discount, liquidity of fund shares, non-diversified, and index-related concentration risks, all of which may adversely affect the Fund. Medium-, and large-capitalization companies may be subject to elevated risks.
Investing involves substantial risk and high volatility, including possible loss of principal. An investor should consider the investment objective, risks, charges and expenses of a Fund carefully before investing. To obtain a prospectus and summary prospectus, which contain this and other information, call 800.826.2333 or visit vaneck.com. Please read the prospectus and summary prospectus carefully before investing.
© Van Eck Securities Corporation, Distributor, a wholly owned subsidiary of Van Eck Associates Corporation.
Related Funds
Important Disclosures
This is not an offer to buy or sell, or a recommendation to buy or sell any of the securities, financial instruments or digital assets mentioned herein. The information presented does not involve the rendering of personalized investment, financial, legal, tax advice, or any call to action. Certain statements contained herein may constitute projections, forecasts and other forward-looking statements, which do not reflect actual results, are for illustrative purposes only, are valid as of the date of this communication, and are subject to change without notice. Actual future performance of any assets or industries mentioned are unknown. Information provided by third party sources are believed to be reliable and have not been independently verified for accuracy or completeness and cannot be guaranteed. VanEck does not guarantee the accuracy of third party data. The information herein represents the opinion of the author(s), but not necessarily those of VanEck or its other employees.
MSCI EAFE Index captures large and mid cap representation across developed markets around the world, excluding the U.S. and Canada.
MSCI EAFE Analyst Sentiment Select Index is based on the MSCI EAFE Index, its parent index. The index uses an optimization process that aims to maximize the exposure to the Analyst Sentiment factor, while controlling for active risk, active specific risk and net ex-ante beta relative to the parent index.
MSCI EAFE Growth Index is based on the MSCI EAFE index, its parent index, and tracks large- and mid-cap growth stocks across developed markets, excluding the U.S. and Canada.
MSCI EAFE Value Index is based on the MSCI EAFE index, its parent index, and tracks large- and mid-cap value stocks across developed markets, excluding the U.S. and Canada.
MSCI EAFE Momentum Index is based on the MSCI EAFE index, its parent index, and tracks large- and mid-cap stocks with high price momentum across developed markets, excluding the U.S. and Canada.
Holdings will vary for the VEFA and its corresponding Index. Visit vaneck.com/vefa for a complete list of holdings in the ETF.
Index returns are not Fund returns and do not reflect any management fees or brokerage expenses. Certain indices may take into account withholding taxes. Investors can not invest directly in the Index. Returns for actual Fund investors may differ from what is shown because of differences in timing, the amount invested and fees and expenses. Index returns assume that dividends have been reinvested. Past performance is no guarantee of future results.
An investment in the Fund may be subject to risks which include, among others, risks related to investing in foreign securities, foreign currency, financials sector, industrials sector, health care sector, special risk considerations of investing in European, Japanese and United Kingdom issuers, depositary receipts, equity securities, issuer-specific changes, medium- and large-capitalization companies, market, operational, index tracking, authorized participant concentration, new fund, no guarantee of active trading market, trading issues, passive management, fund shares trading, premium/discount, liquidity of fund shares, non-diversified, and index-related concentration risks, all of which may adversely affect the Fund. Medium-, and large-capitalization companies may be subject to elevated risks.
Investing involves substantial risk and high volatility, including possible loss of principal. An investor should consider the investment objective, risks, charges and expenses of a Fund carefully before investing. To obtain a prospectus and summary prospectus, which contain this and other information, call 800.826.2333 or visit vaneck.com. Please read the prospectus and summary prospectus carefully before investing.
© Van Eck Securities Corporation, Distributor, a wholly owned subsidiary of Van Eck Associates Corporation.